Venture Market Update - October 28, 2026: Anthropic's Public Filing, AI Megarounds for Flapping Airplanes and Legora, Robotics Valuations Surge, New Venture Funds, and Europe's Nine-Month Review
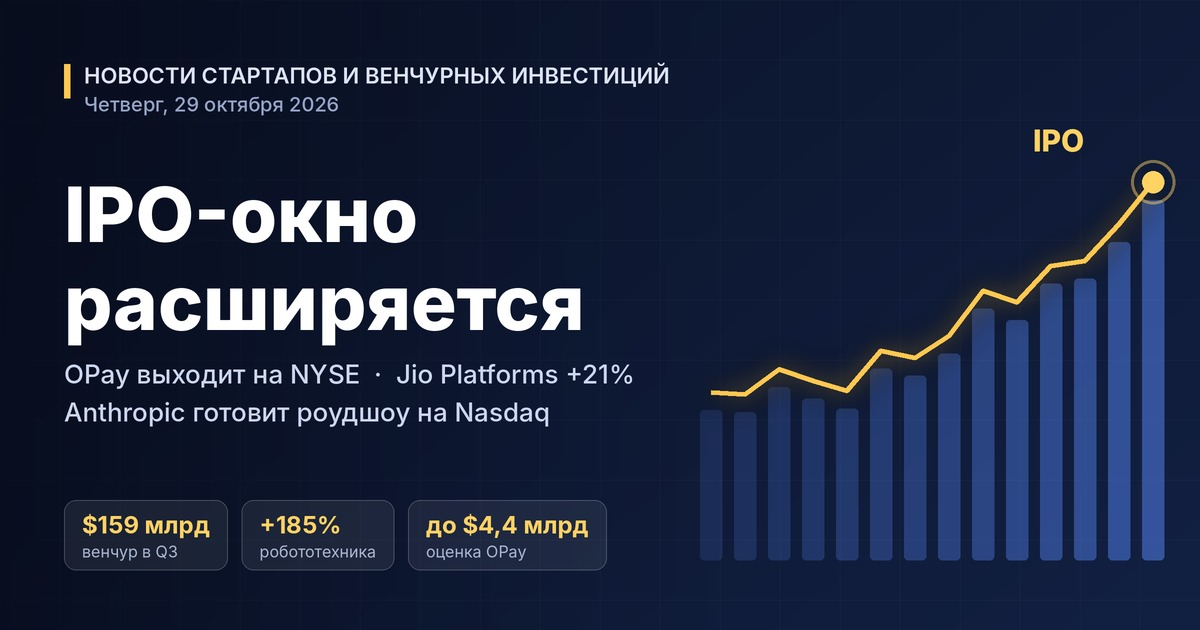
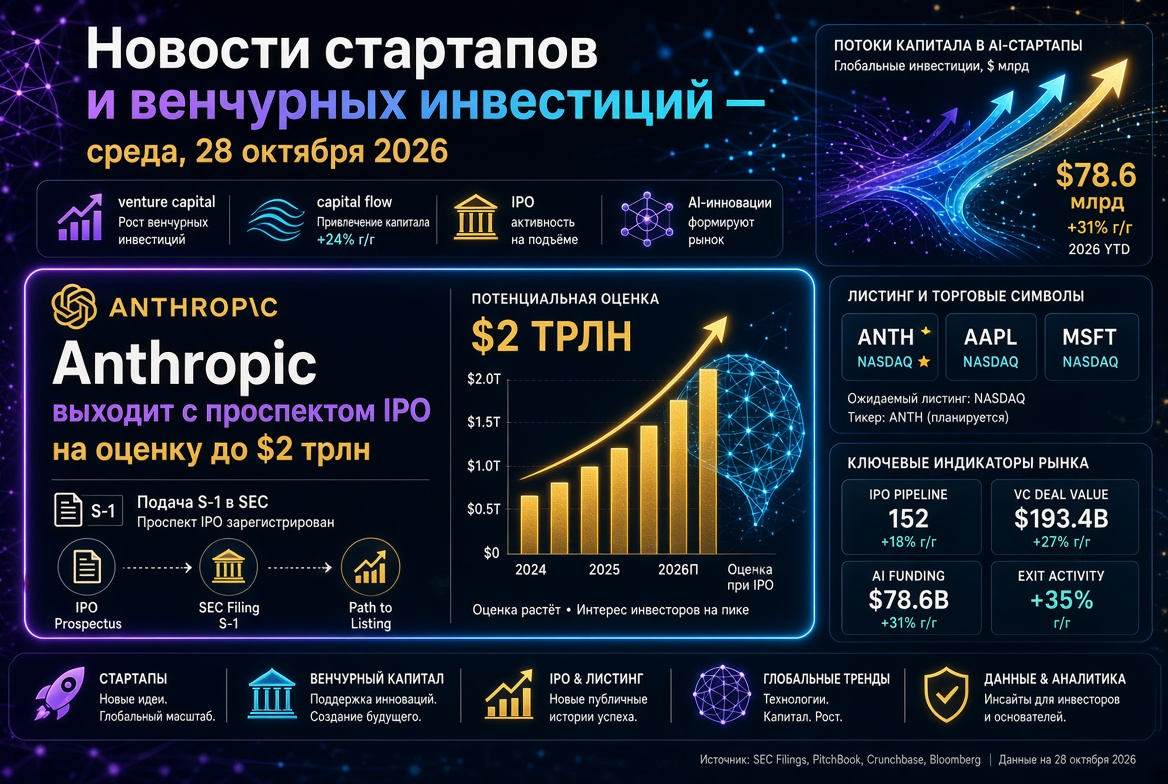
The venture market enters the last week of October with the year’s headline event. Anthropic has filed its S-1 form and is preparing an offering that could become the largest IPO in history. For venture investors and funds, this is more than just a single deal. The valuation that the public market assigns to the leader in generative artificial intelligence will set benchmarks for the entire segment. It will influence late-stage rounds, secondary transactions, and exit strategies for years to come.
Meanwhile, the influx of capital into startups shows no signs of slowing down. From October 15 to October 23 alone, U.S. companies raised over $6 billion across more than fifteen rounds. Key themes of the week for investors include:
- Anthropic IPO: public S-1 filing, ANT ticker on Nasdaq, estimated valuation of $1.5–2 trillion.
- AI Megarounds: Flapping Airplanes, Legora, Tenstorrent, and Modal Labs raising hundreds of millions and billions of dollars.
- Physical AI: Bedrock Robotics and Eka Robotics rapidly increasing valuations.
- Defense and Government Technologies: ASI and 22one receiving backing from leading funds.
- Europe and Emerging Markets: record-breaking nine months and closures of new venture funds.
Anthropic Publishes S-1: The Largest IPO in History on the Horizon
On October 26, Anthropic PBC transitioned its confidential filing submitted on June 1 to public status. The company plans to list on the Nasdaq Global Select Market under the ANT ticker. Goldman Sachs is the lead underwriter, followed by Morgan Stanley, with more than twenty banks participating in the syndicate.
According to business reports, the offering is targeted for the week of November 16. The fundraising could exceed $100 billion, with a valuation of $1.5–2 trillion. For comparison, SpaceX went public in June with a valuation of $1.77 trillion and raised around $86 billion. The pricing, share count, and final deal volume have yet to be specified in the prospectus.
Key financials from the S-1 include:
- Revenue for the first half of 2026 was $16.29 billion, up from $1.16 billion the previous year.
- Revenue for the second quarter was $11.56 billion, with operating income of $974 million.
- Net loss for the semester was $80.75 billion, primarily non-cash, related to the revaluation of convertible notes amid the company's rising valuation.
- The most recent private round was Series H at $65 billion, with a valuation of $965 billion (May 2026).
Multiples and Risks: How the Market Will Value AI Businesses
Analysts are calling Anthropic’s IPO a referendum on the artificial intelligence business model. Annual revenue calculated based on the second quarter stands at approximately $46 billion, suggesting that a $2 trillion valuation corresponds to about 43 times annual revenue. The May private round occurred at around 21 times revenue.
Key considerations for institutional investors include:
- Cost of Computation. Infrastructure costs are rising along with revenue. Experts recommend monitoring the revenue-to-computation cost ratio.
- Long-term Commitments. Multi-year contracts for data centers and chips are putting pressure on cash flow.
- Competitive Landscape. OpenAI is postponing its IPO to next year and reportedly raising another $30 billion privately at a valuation of $1.25 trillion.
Some observers are warning that capital availability for AI companies may decrease. This is why the success of the IPO is critical for the entire venture ecosystem.
AI Megarounds of the Week: Betting on Efficiency and Vertical Solutions
While the market awaits ANT, private capital continues to concentrate in the artificial intelligence segment. The largest deals of recent days include:
- Flapping Airplanes — $1 billion in Series A round at a valuation of $6 billion, quadrupling since January. The round was led by Index Ventures and Lux Capital, with participation from GV, Sequoia, Kleiner Perkins, and Nvidia. The company is developing training methods for large models using significantly less data.
- Legora — $550 million in Series E round at a valuation of $8.8 billion. The Swedish legal platform secured backing from Atreides Management, Fidelity, Baron Capital, and JPMorgan.
- Tenstorrent — $1.5 billion in Series E round at a valuation of $6.2 billion focused on AI chips based on RISC-V architecture.
- Modal Labs — $750 million in Series D round at a valuation of $15.75 billion led by Accel. The company is building cloud infrastructure for AI workloads.
- Town — $108 million in Series B for an AI assistant for teamwork. The round includes investments from Forerunner, Menlo Ventures, and a16z.
The trend is clear: investors are willing to pay a premium for technologies that reduce AI costs (data, chips, computation) and for vertical applications with rapid monetization.
Physical AI and Robotics: Valuations Rising Faster Than the Market
Robotics is becoming the second most significant area for venture investments, following language models. Bedrock Robotics, a developer of autonomous systems for construction equipment, reportedly raised $600 million in a Series C round at a valuation of $4.1 billion. In February, the company was valued at $1.75 billion. Demand is fueled by the construction of data centers and a shortage of heavy equipment operators.
Other notable deals include:
- Eka Robotics — $150 million in Series A round at a valuation of $1.45 billion. The round was led by a16z and F-Prime, positioning the company as a "unicorn".
- Enact — $30 million at the pre-seed stage from Firstminute Capital and Redalpine for sensory technologies aimed at robot agility.
- Coherence Neuro — $45 million from Founders Fund and OpenAI Startup Fund for neurointerfaces.
Defense, Security, and Government Sector: Sustained Interest from Funds
Defense technologies and solutions for critical infrastructure remain a focus for venture funds. Boston-based ASI raised $325 million in a Series C round at a valuation of $3 billion. The round was led by Spark Capital with participation from Craft Ventures, a16z, and Citadel Securities. The platform assists military, airlines, and dispatchers in managing assets.
London-based 22one, a developer of AI tools for police, is valued at nearly $400 million according to the Financial Times. Investors include Sequoia, General Catalyst, Lux Capital, and Creandum. Watchtower Labs secured $35 million at the seed stage from Shield Capital, Conviction, and Founders Fund.
Fintech and Business Platforms: A Return to High Valuations
Fintech is once again demonstrating high multiples. Ramp raised $1.85 billion at a valuation of $60 billion, led by Dragoneer, making it one of the most expensive private fintech companies in the U.S. Whop, a platform for monetizing online businesses, secured $200 million in Series D round from Sequoia Capital at a valuation of $5.1 billion. London-based Nevis, which automates work for asset managers, closed a Series B round at $70 million led by EQT Ventures.
Europe: Record Nine Months and Focus on Late-Stage Investments
The European venture market is showing solid growth. Key figures include:
- In the third quarter, European tech companies raised €27.8 billion across 732 deals, a 32.4% increase year-on-year.
- Over nine months, funding volume grew by 63% to $61.9 billion despite a 19% decrease in the number of rounds.
- Late-stage investments accounted for 53% of capital, with London attracting around 35%.
Among recent deals are Finnish Volare (€7.1 million for insect protein production) and Swiss Sonexos (CHF 5 million for noise suppression technology). Frankfurt-based QuoIntelligence in the cybersecurity space received investments from former German finance minister Christian Lindner.
New Funds and Emerging Markets, Including Russia and the CIS
Capital continues to flow into niche venture funds:
- Endeavor Catalyst Fund V has closed with oversubscription at $320 million. Assets under management have exceeded $850 million, focusing on emerging markets.
- Nauta achieved the first closing of its sixth fund at €60 million with a target size of €150–200 million for European software and deeptech.
- Indie GO Fund II in Russia aims to raise 5 billion rubles for game studios with export potential. The first closing is expected in Q4 2026.
In India, Live2.ai raised about $14 million in a pre-Series B round led by IvyCap Ventures, while Even Healthcare raised $50 million from Khosla Ventures and Alpha Wave. The early stage segment is active in Central Asia, with the Kazakh AI startup Riasm securing $3 million at the pre-seed stage. In the Russian market, the Moscow venture fund is directing 250 million rubles to tech companies, and the "Creative Venture" fund has invested in the data platform "Argument."
What This Means for Venture Investors: Key Takeaways of the Day
- The Anthropic IPO will set a pricing benchmark. A successful offering will cement high multiples for late-stage AI companies. Weak demand, on the other hand, could lead to the revaluation of private portfolios.
- The window for exits is widening. After SpaceX and Anthropic, other "unicorns" will queue up for the public market.
- Diversification is shifting towards "real" AI. Robotics, defense, and infrastructure are capturing an increasing share of funding rounds.
- Discipline remains key. Concentration of capital among a few leaders raises risks for funds entering deals at peak valuations.
The global startup and venture investment market heads into November with a rare combination of record liquidity and heightened uncertainty. The next three weeks, leading up to the anticipated debut of ANT, will be crucial in shaping investor sentiment worldwide.