Oil Market: First Weekly Correction in Three Weeks
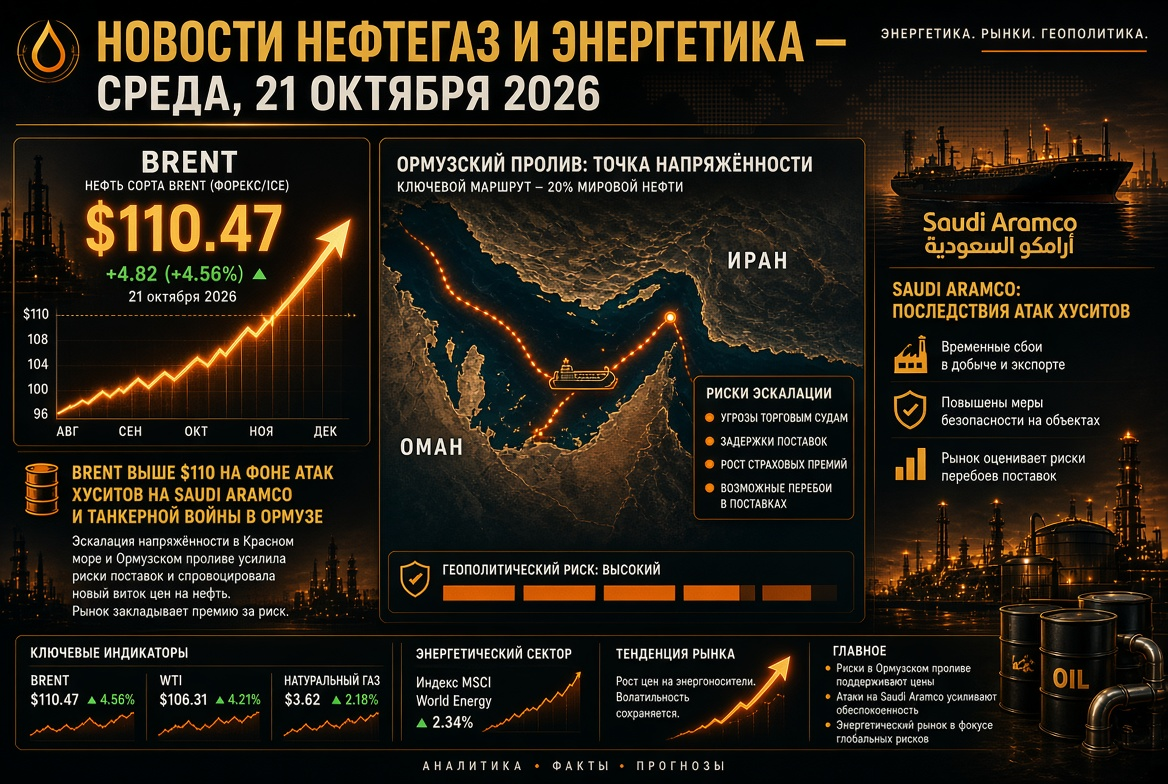
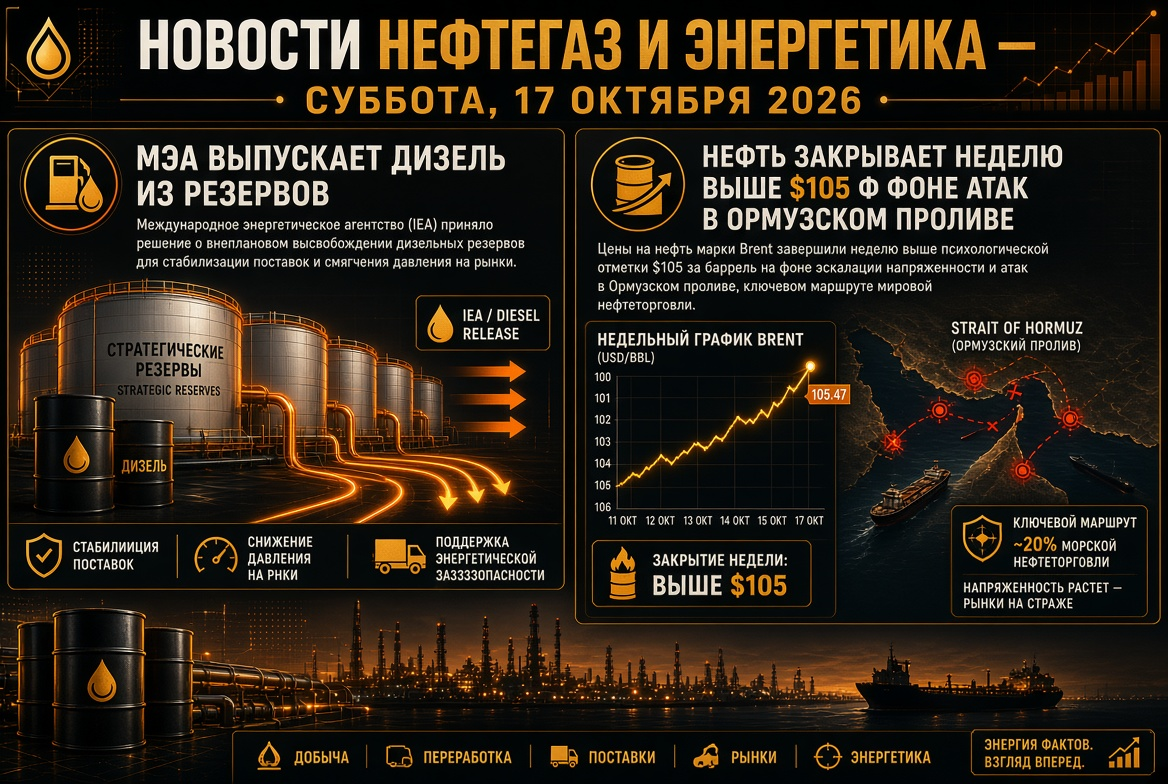
On Friday, oil prices fell for the third consecutive session: Brent dropped to $102.5–103.5 per barrel, while WTI slid to $100, briefly dipping below this threshold. At the week’s end, Brent is down approximately 2%, despite rising to $108 on Monday — nearly a four-month high.
- Wednesday: a sharp decline of nearly 3%, to $105.7 — the steepest drop in three weeks — followed reports of a partial imminent restart of the Saudi East–West pipeline.
- Thursday: Brent closed at $104.82, WTI at $101.91 per barrel.
- Monthly Performance: WTI gained about 18–19%, while Brent rose about 13%; oil prices are more than 50% higher than levels a year ago.
Analysts agree that the fundamental picture does not support a prolonged decline of Brent below $100. The futures curve remains deeply backwardated: the December contract is nearly $5 cheaper than the November one — the market is paying a premium for immediate delivery.
Middle East: East–West Pipeline, Red Sea, and Hormuz
The East–West pipeline, with a capacity of up to 7 million barrels per day, is a key bypass for the Strait of Hormuz, which has seen flows of up to 5 million barrels per day in recent months. Following drone attacks, three pumping stations were damaged, and loadings from Yanbu were suspended. Riyadh expects to restore about half of the capacity in just a few days; full recovery is projected to take five to six weeks.
- Alternative Routes: Saudi Arabia is offering additional batches to Asian refineries via transshipment “ship-to-ship” at the Omani port of Sohar.
- Red Sea: Houthi rebels have taken control of Mocha, Perim Island, and Hanish and announced a blockade of Saudi ports; on Thursday, both sides exchanged strikes across the border again.
- Hormuz: the strait is virtually closed to commercial shipping, and there are no direct negotiations between the US and Iran, with an Iranian port blockade still in place.
- Production: Saudi Arabia reported a production drop in August to its lowest level since 1990.
The IEA warns that supply disruptions are already forcing consumers to reduce oil demand.
Petroleum Products and Refineries: Diesel Remains the Epicentre of Shortage
- The diesel crack spread in the US reached a record $117.97 per barrel on Wednesday; European gasoil is at historical peaks.
- Benchmark diesel in New York is around $5.05–5.25 per gallon; the retail price in the US reached a record $6.23 per gallon, while gasoline stands at $4.32.
- US distillate inventories have risen for the third consecutive week: +1.6 million barrels, reaching 107.9 million barrels — the first sign of cooling.
Diesel in Europe is approximately 70% more expensive than February levels. For refineries outside conflict zones, this is a period of super margins, but for fuel companies, aviation, and logistics, it signifies a shock in costs.
Gas and LNG: Europe Enters Heating Season with 68% Storage
TTF futures rose by 1.5–2% on Friday, reaching €77–78 per MWh after €82 on Wednesday; year-on-year, gas in Europe has appreciated by approximately 140%. EU gas storage is around 68% full — 16 percentage points below the five-year average and near two-decade lows.
- Qatar: force majeure on LNG supplies extended until November; about 17% of Ras Laffan’s capacity is offline, with repairs expected to take three to five years.
- Asia: spot LNG costs $26–28 per million BTU — the highest since 2022; demand for LNG in the region may drop by 3–10% by year-end, with some buyers in South Asia rejecting high-priced offers.
- Norway: scheduled maintenance temporarily reduces pipeline supplies.
- USA: Henry Hub prices are about $2.86 per million BTU; a record spread supports American LNG exporters.
Russia and Ukraine: Ceasefire on Energy Facilities Not Confirmed, Fuel Exports Restricted
The agreement announced by Washington on September 14 to cease strikes on energy facilities is not functioning in practice: refineries in Syzran and Yaroslavl were attacked over the week, and strikes on Ukrainian infrastructure continue. Moscow described the idea as “good,” while Kyiv is prepared for de-escalation with partner guarantees.
- A diesel export ban for producers is reportedly being extended until the end of October; for non-producers, it is in effect until January 31, 2027.
- A full gasoline export ban remains in place until January 31, 2027; the export of jet fuel is limited until November 30.
- Following drone attacks, production has been cut at six major Russian refineries.
For the global market of petroleum products, the absence of Russian diesel is one factor contributing to record premiums in middle distillates.
Asia: India and China Divide Available Barrels
Russian oil imports to India decreased to about 2.1 million barrels per day in August compared to 2.7–2.8 million barrels per day in July, due to refinery maintenance, decreased availability of crude, and aggressive procurement by Chinese processors. The retreat of Brent from peaks provides India with some respite — the rupee remains around 95.8 per dollar. Conversely, the yuan has strengthened to a four-year high, making energy imports cheaper for China.
Electricity, Renewables, and Nuclear: Structural Shift Accelerating
- Renewables: according to the IEA, renewable generation is expected to grow by roughly 1,000 TWh per year until 2030, of which over 600 TWh will come from solar generation; the share of low-carbon sources in global electricity generation will increase from 42% to 50%.
- Nuclear: uranium is around $90 per pound; the US and Saudi Arabia have signed a peaceful nuclear agreement, while South Korea has completed the Saeul 3 energy unit. At the same time, summer droughts have limited the operation of nuclear power plants in Europe.
- Bottleneck: the delivery times for large gas turbines exceed the construction cycle of the power plant itself.
Expensive gas improves the economics of renewables and storage, but rising rates are making capital more expensive for grid and new projects.
Coal: Insurance for Asia’s Energy Systems
Thermal coal in Newcastle is holding steady at about $145 per ton. Northeast Asia is replacing expensive LNG with coal and nuclear generation, sustaining demand for exporters — Australia, Indonesia, Russia, and South Africa. The long-term trend remains unchanged: the IEA forecasts that coal's share in global generation will decline from 34% in 2025 to 27% by 2030, which is why major producers are hesitant to invest in new mines.
Macroeconomics: Rates Rise Amid Energy Inflation
On September 16, the Federal Reserve raised rates by 25 basis points to 3.75–4.00% — the first increase since 2023; on Friday, the Bank of Japan also raised rates. The yield on 10-year US Treasuries is about 4.95%. The number of drilling rigs in the US has increased to 591 (450 oil, 132 gas), compared to 539 a year earlier: shale companies are responding to prices, but cautiously.
What Investors and Energy Sector Participants Should Monitor
- The actual restart of the East–West pipeline and the resumption of loadings from Yanbu.
- Shipping through the Hormuz and Bab-el-Mandeb straits, new strikes on infrastructure.
- The status of the energy ceasefire between Russia and Ukraine and the condition of Russian refineries.
- The official extension of the diesel export ban from Russia.
- The dynamics of TTF, injection rates into EU storage, and competition with Asia for LNG.
- Diesel crack spreads and weekly inventory statistics in the US.
The baseline scenario for the coming days is Brent in the range of $98–108 per barrel, with high sensitivity to news from the Middle East. Petroleum products and gas remain the most strained segments of the global energy market.