Oil Market: Brent Balances Around $100
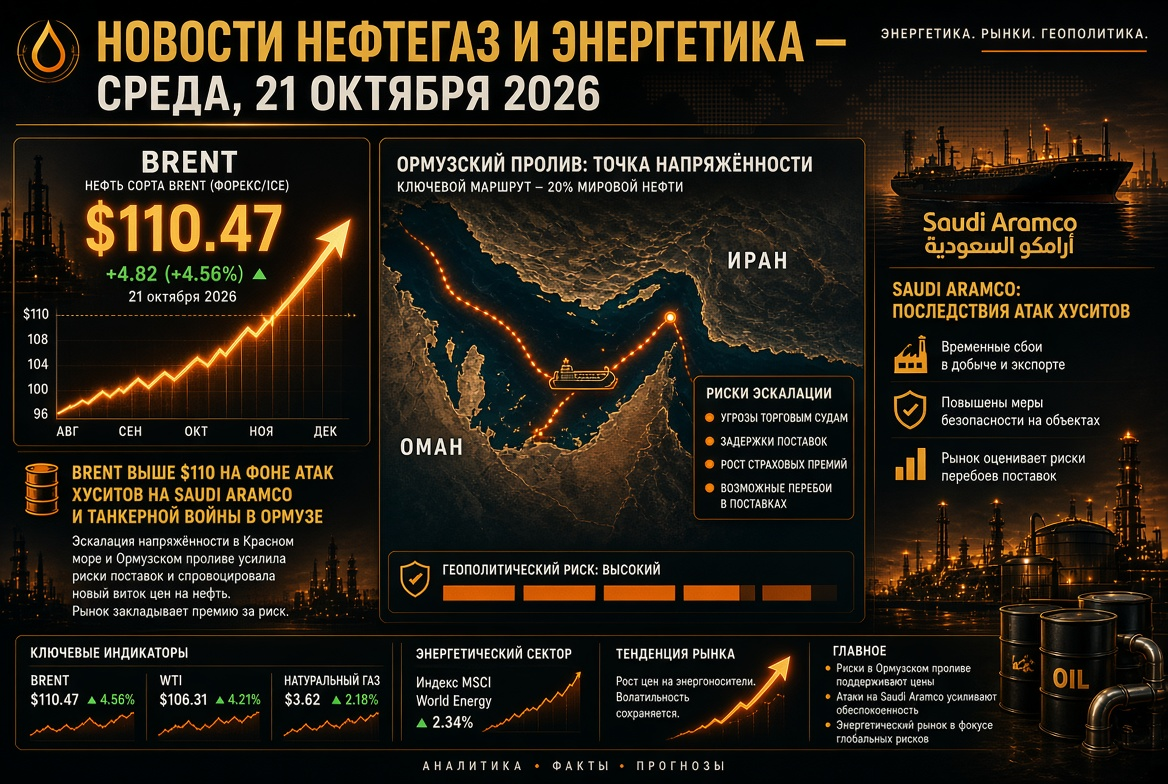
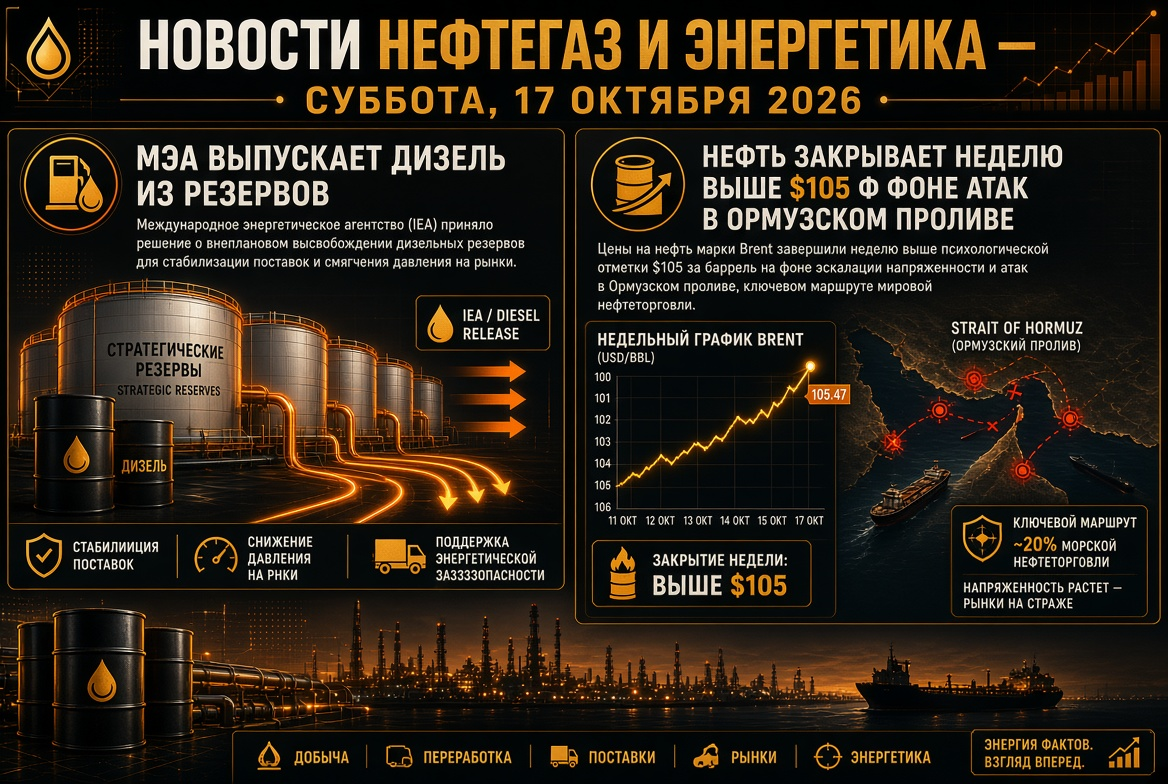
Oil prices close the week with high volatility. On Friday, Brent declined by about 2.5%, dropping to just below $100 per barrel, while WTI fell nearly 4%, heading toward $89. Just the day before, Brent was holding above $102. Despite the correction, crude oil remains approximately 1.5 times more expensive than a year ago.
Prices are influenced by a mix of factors:
- Reserves: The European Commission is discussing timelines for a new coordinated release of strategic stocks with IEA participants.
- Export Recovery: Non-Iranian oil supplies through the Strait of Hormuz returned at the end of September to pre-war levels of 13.5 million barrels per day, according to tracking data, thanks to convoy escorts.
- Security Risks: This week, three tankers in the strait were hit by unidentified projectiles, while talks between the U.S. and Iran remain stalled.
- Stocks: According to the U.S. Department of Energy, global oil reserves have decreased by approximately 400 million barrels since the beginning of the year.
OPEC+: Meeting on October 4 and Quota Issues for 2027
On Sunday, October 4, seven key OPEC+ participants—Saudi Arabia, Russia, Iraq, Kuwait, Kazakhstan, Algeria, and Oman—will hold their monthly meeting. According to sources, November quotas are expected to remain unchanged. The formal target levels have long diverged from reality: the actual production of the alliance is about 5 million barrels per day below pre-war figures, as Gulf countries struggle to fully export their crude.
The main intrigue shifts to 2027: the alliance is concluding an audit of production capacities, based on which new baseline production levels will be determined. For oil companies and investors, this is a question of long-term market share distribution.
Petroleum Products and Refineries: Diesel Becomes the Main Shortage
The market for petroleum products is currently tighter than the crude oil market. Diesel fuel is setting price records in many countries, surpassing $6 per gallon in the U.S. In just a few days, supply has decreased across several fronts:
- China has halted the export of gasoline, diesel, and jet fuel for October, except for shipments to Hong Kong and Macau. Domestic fuel inventories have fallen to multi-year lows, with a decision on resumption expected after the holidays ending on October 7.
- Russia has extended its ban on diesel exports for producers until October 31.
- India: An explosion at a major export-oriented refinery has led to the cancellation of several tenders.
- U.S. is considering a ban on diesel exports if Germany and France do not release fuel from reserves. American refineries are operating at about 97% capacity, and Washington itself acknowledges that the ban could lead to higher gasoline prices.
Germany and France account for approximately 35% of the EU's strategic diesel reserves, estimated at 39 million tonnes—over two months of consumption. Analysts expect that an American ban would hit Latin America hardest. The UN warns that global fuel subsidies could exceed $1 trillion.
Gas and LNG: Europe Enters Winter with Supply Deficits
The European gas market remains one of the most vulnerable segments of the energy sector. Prices at the TTF hub are holding around €73 per MWh, nearly double last year's levels. EU underground storage is only 71.5% full—about 20 percentage points below the seasonal norm.
- Germany has instructed SEFE to inject an additional 8 TWh of gas into storage facilities.
- The EU is considering a one-year extension of methane regulations for imported gas to avoid limiting LNG supplies.
- The head of Japan's JERA warned that LNG prices have yet to exhaust their growth potential.
- LNG imports to China are declining for the second consecutive month, while Pakistan is exploring direct purchases for power plants.
Long-term investments in the sector are accelerating: ConocoPhillips has signed a 20-year LNG contract with Venture Global, while Shell has approved the second phase of LNG Canada, which will double the project's export capacity.
Coal: Prices in China at Three-Year High
Coal is once again serving as the safety net for energy systems in Asia. The benchmark price for thermal coal at the Qinhuangdao port has risen for 11 consecutive weeks, reaching 986 yuan (approximately $147) per tonne—the highest in three years. Since mid-July, prices have increased by 24% due to reduced domestic production following safety inspections and a nearly 25% reduction in imports from Indonesia.
Coal accounts for nearly half of electricity generation in China, and authorities have urged mines to maintain stable production. In India, the IEA expects coal demand to grow by 4.2% this year, reaching 1.353 billion tonnes.
Electricity, Renewables, and Nuclear Power
Global electricity demand is growing at its fastest pace in 15 years—driven by data centers, artificial intelligence, and electrification. Grids and generation cannot keep pace with consumption, especially in emerging markets.
- India: The electricity deficit in September reached 560 million kWh—its highest since August 2023. Nearly 40% of coal power plants are operating at critically low fuel levels. Renewable energy generation increased by 25.1%, but its share in overall generation declined to 17%.
- Nuclear Energy: Amazon has signed a 20-year agreement for nuclear electricity supply with Constellation, and uranium prices have hit record highs.
- Europe: Three EU countries have advocated for a new renewable energy target by 2040.
The energy crisis enhances the arguments for renewables, storage, and nuclear power as tools for energy security, not just climate policy.
Asia: India and China Reshape Imports
India is increasing purchases of Middle Eastern oil while reducing Russian flows, with its refiners seeking tankers for voyages through Hormuz. New Delhi emphasizes that high prices are caused by chaos in shipping, not a shortage of raw materials. The rise in oil prices has already led to an outflow of $3.2 billion in foreign investments from Indian markets. Analysts have also lowered their forecast for China's oil imports in the fourth quarter by 400,000 barrels per day. Taiwan has allocated $13 billion to protect consumers from high energy costs.
Russia: Export Restrictions and Domestic Fuel Market
The Russian petroleum products market remains under strict regulation. In addition to the ban on diesel exports for producers until the end of October, there is also a ban on gasoline exports until the end of January and restrictions on jet fuel exports until November. Authorities explain these measures by high demand during the harvest season and the need to replenish stocks after drone attacks on refineries. Retail gasoline prices have risen by approximately 21% since the beginning of the year, and the antitrust agency is investigating dozens of independent gas station networks.
What to Watch for Investors and Energy Sector Participants
- October 4: OPEC+ decision on November quotas and signals regarding 2027 parameters.
- October 7: Conclusion of holidays in China and possible resumption of fuel exports.
- IEA and EU Reserves: Volume and timelines for releasing oil and diesel.
- U.S. Decision on diesel export ban and refining margins’ reaction.
- Strait of Hormuz: Shipping security and progress in U.S.-Iran negotiations.
- Weather in Europe: Early cold spells with storage at 71.5% could sharply raise gas and electricity prices.
The baseline scenario for the coming days is high volatility: oil reacts to news about reserves and the Hormuz, while petroleum products, gas, and coal remain structurally deficit. For oil and fuel companies, this means high refining margins, while consumers and importers will continue to face pricing pressure.