Main Highlights for Wednesday Morning
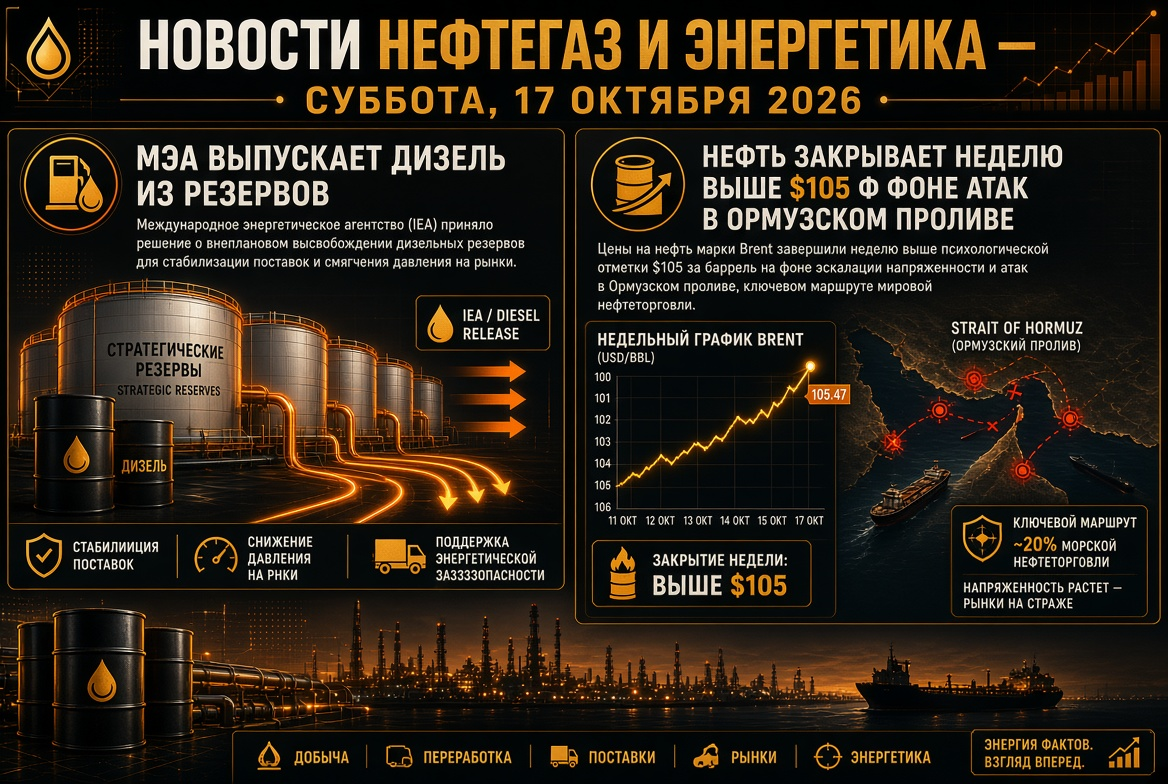
- Oil: Brent is around $105–106 per barrel, WTI is around $93; prices had climbed above $107 the previous day.
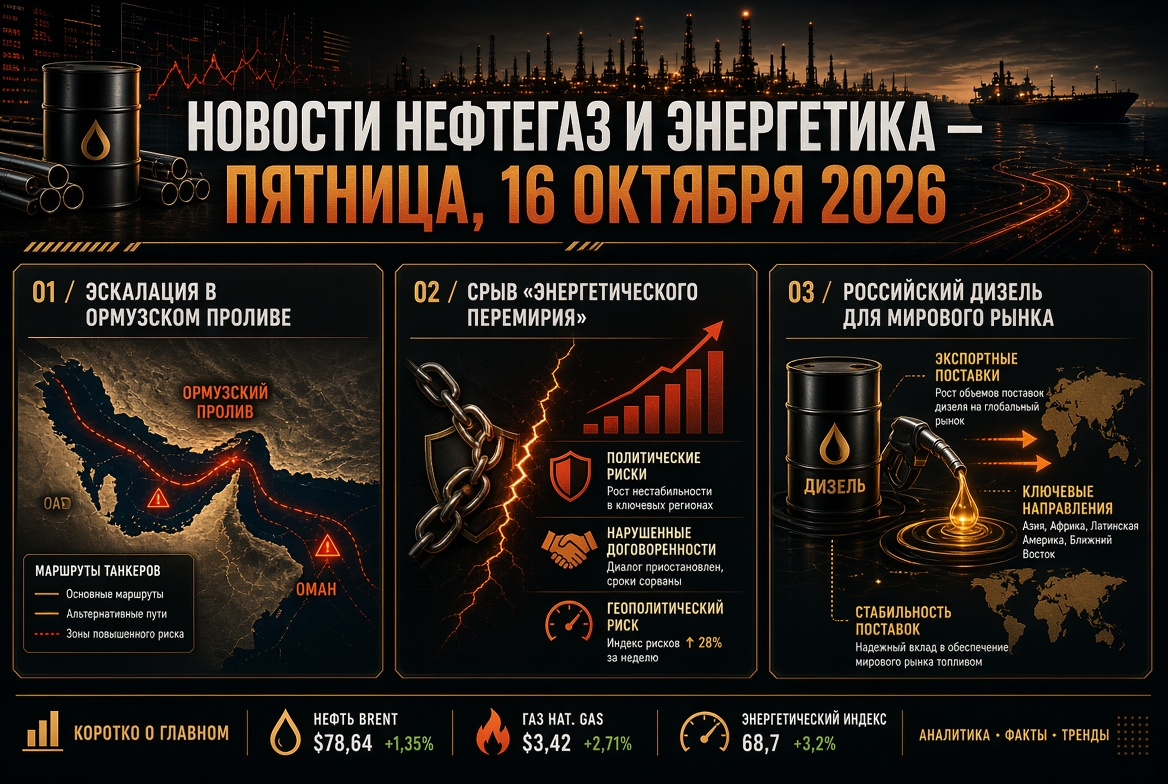
- Oil Products: Russia has partially lifted its ban on diesel exports and is releasing 500,000 tonnes to the global market.
- Gas: TTF trades around €83 per MWh, a maximum since the beginning of 2023; EU gas storage is approximately 73% full.
- OPEC+: quotas for November remain unchanged, with the next meeting scheduled for 1 November.
- Geopolitics: attacks on tankers at the Strait of Hormuz and assaults by Houthis on Saudi Arabia maintain risks for supply chains.
Oil Market: Risk Premium Keeps Brent Above $100
On Tuesday, oil corrected by approximately 1% after nearly $2 rise on Monday, when Brent closed at a maximum since mid-September. The US-Iran conflict has now entered its eighth month, and the market continues to assess primarily the physical availability of barrels rather than supply-demand balance.
Supporting Factors
- A drone strike on a tanker near the Omani port of Sohar and damage to another vessel in the Strait of Hormuz; at least nine attacks have been reported since the start of October.
- Attacks by Houthis on Riyadh airport heightened concerns regarding Saudi infrastructure.
- High shipping and insurance costs widen the spread between Brent and WTI.
Restraining Factors
- Expectations of additional volumes of Russian diesel.
- Recovery of production in the Gulf of Mexico following Hurricane Isaias.
- Weak demand: OPEC has lowered its forecast for oil consumption growth in 2026 to 0.4 million barrels per day, from 1.4 million at the start of the year.
OPEC+ and Oil Price Forecasts
The seven OPEC+ countries — Saudi Arabia, Russia, Iraq, Kuwait, Kazakhstan, Algeria, and Oman — have maintained a pause in production increases for the second consecutive month: the total quota for November stands at 31.01 million barrels per day. The actual production of the alliance remains below target levels due to export restrictions through the Strait of Hormuz.
Analyst estimates vary:
- Goldman Sachs has raised its Brent price forecast for December to $90 from $85, estimating the risk premium at slightly over $20 per barrel.
- The US Energy Information Administration forecasts an average of $105 in the fourth quarter and $84 in 2027.
- The consensus survey of analysts yields an average Brent price of around $89 for 2026.
Oil Products and Refineries: Diesel Crisis Receives Respite
The middle distillates market remains the most stressed segment of the energy sector. The gasoil premium to Brent approached $98 per barrel last week: the deficit is concentrated not in crude oil, but in refining. US refineries are operating at approximately 96% capacity, with almost no spare capacity.
- Russia: as of 10 October, the export of 500,000 tonnes of diesel fuel has been permitted; Washington discusses the possibility of additional supplies of up to 3 million tonnes. The US has temporarily lifted sanctions on Russian fuel.
- China: after a week-long pause, Beijing has approved exports of gasoline, diesel, and jet fuel for October, amounting to about 3.7 million tonnes.
- IEA: the agency has urged member countries to accelerate the release of reserves with a priority for diesel.
Gasoil futures on ICE reacted with a 2.3% decline, falling to $1,449 per tonne. The effect may be limited: Russian refining has significantly suffered from drone attacks, while the permitted volume is comparable to one day’s consumption in the US. Gasoline prices in the US average $4.36 per gallon.
Gas and LNG: Europe Enters Winter with Record Low Reserves
The European gas market remains the main source of concern for the energy and industrial sectors. Without Qatari LNG, TTF futures hover around €83 per MWh — about 2.5 times higher than a year ago.
- EU storage is filled to 73% against a seasonal norm of about 90% — the worst level recorded since observations began in 2011.
- The target fill level has been relaxed from 90% to 80%.
- In the event of a cold winter, the bloc may need to cut demand by 7%, or 14 billion cubic meters.
- From 1 January 2027, a complete ban on imports of Russian LNG will come into effect.
Forecasts for winter are polarised: from €56 in Citi’s baseline scenario, where demand has already decreased due to industrial stoppages, to €85–100 and above from Morgan Stanley in the event of frosts and new supply interruptions.
Electricity and Renewables: Renewable Generation Mitigates Gas Shock
The high gas prices are accelerating structural shifts in electricity generation. In the first half of 2026, solar generation in the EU reached record levels, wind generation increased, and wholesale electricity prices in several countries are increasingly diverging from gas prices. The downside is the growth of hours with negative prices and evening price peaks, which enhances the investment attractiveness of energy storage systems.
In the US, a record introduction of about 86 GW of new capacity is planned for 2026, of which around 93% will come from solar, wind, and battery sources. For investors, the renewables sector and grid infrastructure remain a defensive narrative amid the volatility of hydrocarbons.
Coal: Demand Supported by High Gas Prices
The coal market is benefiting from the gas deficit. Rising gas prices following the onset of the Middle Eastern conflict have enhanced coal's competitiveness in generation, and energy coal prices in 2026 have recovered from the lows of late 2025. The main demand is driven by China, India, and Southeast Asian countries, while in Europe, coal-fired plants are serving as reserves in case of a cold winter. In the long term, shipments of energy coal by sea are expected to decline, according to industry analysts.
Geopolitics and Sanctions: Energy Truce in Question
The US President announced an energy truce between Russia and Ukraine; however, on Monday, Kyiv accused Moscow of violating it. For the market, this means ongoing risks for Russian refineries and export infrastructure. Concurrently, the temporary easing of sanctions on Russian fuel has been the first practical step by Washington to expand the supply of oil products.
What Matters for Investors and Energy Sector Participants
- Strait of Hormuz: every new attack on tankers adds several dollars to oil prices; de-escalation could quickly remove a significant part of the premium.
- Diesel and Refinery Margins: actual shipments from Russia and China will indicate whether the oil products market has reached its peak.
- Gas: weather forecasts for November and the withdrawal rates from EU storage will determine TTF dynamics.
- Statistics: the focus will be on weekly data on US oil and oil products inventories and fresh monthly oil market reviews.
- OPEC+: the meeting on 1 November will show whether the alliance is ready to resume production growth.
The baseline scenario for the coming days is high volatility: oil, gas, and oil products remain at the mercy of news from the Middle East, while electricity and renewables receive additional momentum from high hydrocarbons prices.