Oil market: Brent at $115, WTI above $100
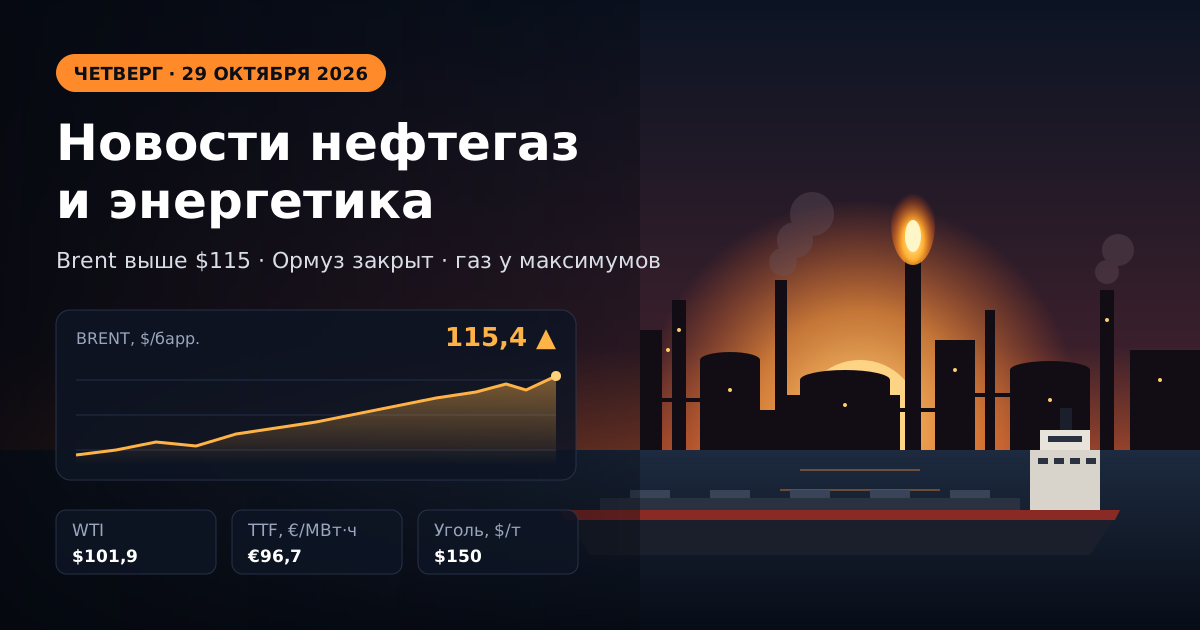
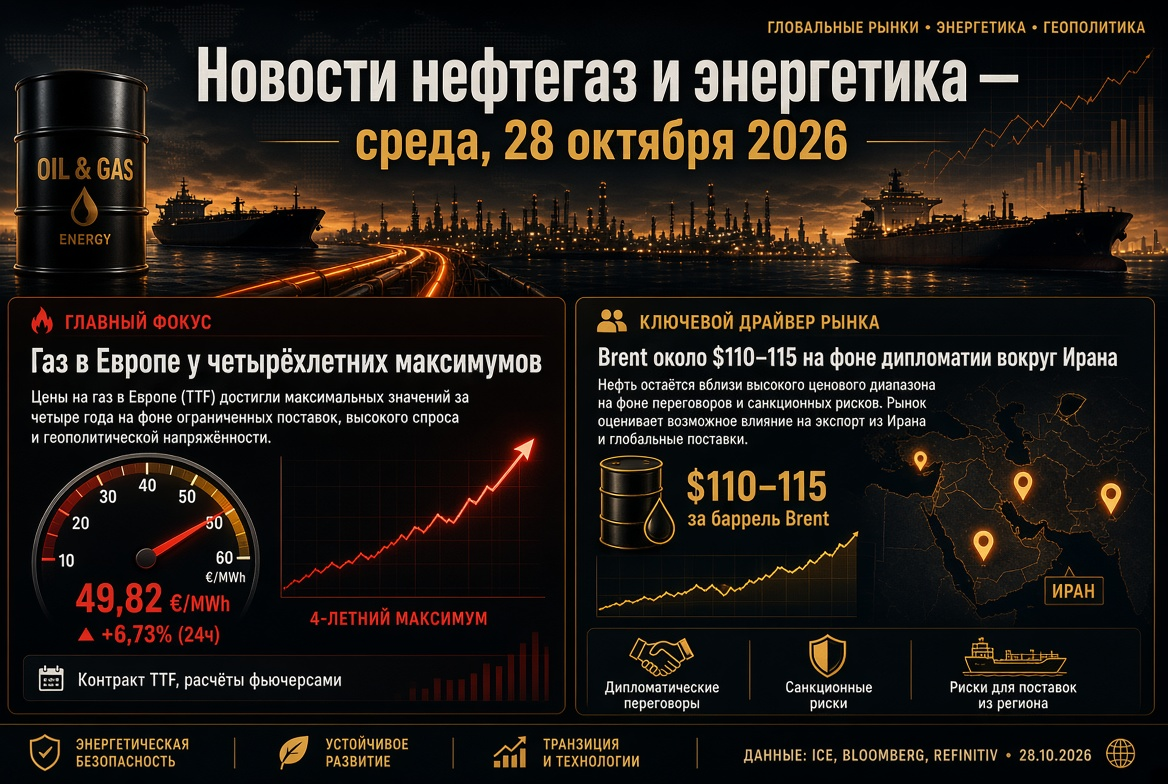
At the close of trading on 28 October, the December Brent futures contract on ICE was up about 1.2–1.4% and held in the range of $114.7–115.5 per barrel, recovering the previous session's decline. US WTI strengthened to $101–102. Over the month, Brent gained roughly 20%, and almost 80% year-on-year.
Key drivers of oil prices
- Strike on Ras Tanura. The Houthis claimed a missile attack on a refinery with a capacity of 550,000 barrels per day. Riyadh did not confirm the strike, but Ras Tanura is one of the kingdom's two main export hubs, and the market immediately priced in the risk.
- US inventories. The API recorded a drawdown in crude stocks of 2.03 million barrels against an expected build of 0.8 million, which supported WTI.
- Political uncertainty. The Israeli elections ended in a de facto stalemate: neither Benjamin Netanyahu nor Gadi Eisenkot secured a clear path to a majority.
- Curve structure. The January Brent contract is trading noticeably below December (around $111), while the Brent–WTI spread has widened to about $14 — the war premium is concentrated in the European benchmark.
Strait of Hormuz: the main risk to global oil and LNG supply
The Islamic Revolutionary Guard Corps officially declared the strait closed on 26 October, and the International Maritime Organization warned on 27 October of mine hazards along the route and the impossibility of guaranteeing safe passage. The Iranian side reported a tanker catching fire after hitting a mine on an "unauthorised" route and extended the blockade to the Gulf of Oman.
On the negotiating track, Tehran has put forward seven conditions for reopening the strait, including the lifting of the US naval blockade, an exemption for oil sanctions and the unfreezing of at least $12 billion in assets. According to the Iranian side, tanker traffic could be restored within 4–5 days after the demands are met. An important detail for the market: taking alternative routes into account, Middle East oil exports in the week to 18 October exceeded 24 million barrels per day, that is, above the pre-war level. The physical deficit is thus partially offset, but freight and insurance costs remain extreme.
OPEC+: the 1 November meeting and 2027 quotas
Seven key members of the alliance — Saudi Arabia, Russia, Iraq, Kuwait, Kazakhstan, Algeria and Oman — will meet on Sunday, 1 November. In October and November, quotas were kept unchanged: 10.5 million bpd for Saudi Arabia, 9.9 million bpd for Russia, 4.4 million bpd for Iraq.
- The seven members' actual output in August was about 25 million bpd — roughly 5 million bpd below the pre-war February level.
- Quota increases for 2026 remained largely on paper due to disruptions to exports through Hormuz.
- The review of production capacities required to allocate quotas for 2027 has been postponed; the market's base case is that current policy will be maintained.
Gas and LNG: Europe enters winter with the lowest storage since 2009
The Dutch TTF hub is trading at around €96–97 per MWh — the highest since December 2022. Since the start of the year, European gas prices have more than tripled. EU underground storage is about 74.6% full — the lowest level for this time of year on record, roughly 14 percentage points below the five-year average.
- The loss of Qatari LNG remains the key factor behind the deficit in the liquefied natural gas market.
- Competition with Asia for flexible LNG cargoes is forcing Europe to pay a premium.
- Norwegian supplies were constrained in autumn by unplanned maintenance.
- Henry Hub in the US remains around $3 per MMBtu, which strengthens the economics of US LNG exporters.
For Europe's energy-intensive industry and power generation, this means high electricity prices at the winter peak and the risk of consumption curtailment in cold weather.
Russia: record export revenue and signals of sanctions easing
Seaborne exports of Russian oil rose to 3.85 million bpd in the week to 25 October, and their weekly value reached $2.76 billion — the highest of the entire conflict period. The decline in the Urals price was offset by higher shipments and a rise in ESPO. At the same time, the four-week average fell to 3.55 million bpd, and traders expect a reduction in shipments from western ports in November due to higher refinery runs and the end of navigation on the Northern Sea Route.
Sanctions agenda
- On 28 October, the fourth tanker with Russian diesel was dispatched for export under the Moscow–Washington arrangement of 9 October.
- According to the business press, the parties are discussing the return of US companies to the Russian oil market and the resumption of Druzhba pipeline supplies to Europe.
- Hungary is seeking an extension of the US exemption for purchases of Russian oil, which expires on 21 November.
Oil products and refineries: diesel shortage and domestic market regulation
The oil products segment remains the most stressed link in the global fuel and energy sector. In the US, distillate inventories have remained noticeably below the five-year norm throughout autumn, and refinery utilisation is declining with seasonal maintenance.
Russia has imposed a ban on exports of petrol, diesel and marine fuel from 1 August 2026 to 31 January 2027, with quotas for some diesel exporters. The average retail price of a litre of petrol in mid-October was about RUB 78.7. The Ministry of Energy has proposed options to the government for supporting fuel imports, one of which envisages raising retail prices by RUB 2.1 per litre. Drone attacks on refineries, prolonged maintenance and sanctions restrictions on equipment continue to weigh on refining margins.
Coal and power: the return of coal in Asia
Newcastle thermal coal is holding at around $150 per tonne, having gained more than 40% over the year; on 6 October, prices reached $152.2 — the highest since October 2024. Expensive LNG is encouraging a switch by Asian power generation to coal, while uncertainty over Indonesia's export rules is delaying negotiations on 2027 contracts. For coal companies in Australia, Indonesia, Russia and South Africa, this is a window of elevated profitability.
Renewables and the energy transition: records amid crisis
According to IEA estimates, in 2026 renewables will overtake coal as the world's largest source of electricity generation for the first time, and solar generation will surpass wind. In India, solar and wind output rose by more than 25% in the first half of the year. The energy crisis is accelerating investment in renewables, energy storage systems and grids, yet evening demand peaks are still covered by gas and coal, and the lack of flexibility is leading to more frequent negative prices on the wholesale market.
What matters for investors and fuel and energy market participants on 29 October
- Hormuz and Iran: any signals of progress in negotiations could quickly remove part of the premium from Brent; escalation ahead of the US midterm elections on 3 November could open the way to $120.
- Confirmation of damage at Ras Tanura: a key factor for the oil products market in Asia and the Middle East.
- OPEC+ on 1 November: quotas are expected to be maintained; a discussion of 2027 quotas would come as a surprise.
- Gas: weather forecasts and the pace of withdrawals from underground storage will determine whether TTF holds below €100.
- Sanctions against Russia: decisions on Hungary, the "diesel deal" and access for US companies are an indicator of a possible reshaping of global oil flows.
The oil and gas market at the end of October 2026 remains a market of supply and geopolitics: oil, gas, coal and oil products are all trading at a risk premium at the same time, and the energy transition is accelerating precisely against the backdrop of the crisis in conventional energy carriers.