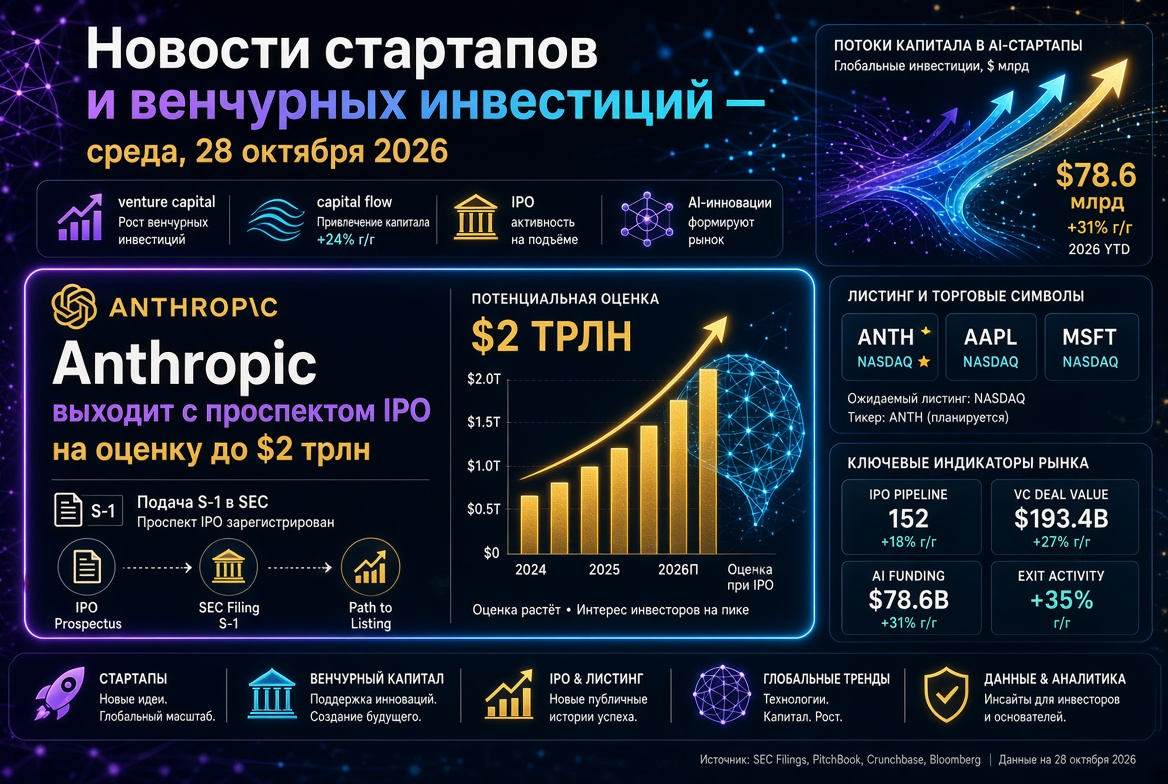
Key agenda topics for venture investors and funds on Wednesday, October 21, 2026:
- OpenAI is looking to raise around $30 billion at a valuation exceeding $1.4 trillion ahead of Anthropic’s IPO, expected in mid-November.
- AI infrastructure continues to be the main magnet for venture capital: Modal, Nscale, and Verda closed significant rounds.
- New unicorns: Town reached a valuation of $1 billion, and Dream Labs raised $90 million for robotics.
- Fintech and defense technology show steady demand from funds.
- Market risks: corrections in semiconductors and the debt load of data centers are restraining valuations.
OpenAI vs. Anthropic: The Battle for Institutional Capital
The most discussed story of the week is OpenAI's attempt to secure a round of about $30 billion at a fixed pre-investment valuation of $1.4 trillion. According to sources, existing shareholders such as SoftBank and Abu Dhabi's MGX are involved in the negotiations, with UAE funds collectively discussing investments of up to $10 billion. Interest is also being shown by BlackRock and the University of California endowment.
Why OpenAI Is in a Rush
- Competition for funds. Anthropic held an investor day on October 14 and is preparing for listing; both companies are addressing the same sovereign funds and long-only investors.
- Infrastructure commitments. The companies need a liquidity buffer in case a market slowdown postpones their own listing, planned for 2027.
- Valuation growth. $1.4 trillion is approximately 64% higher than the March round of $122 billion at a $852 billion valuation, corresponding to a multiple of around 28x on annual revenue of $50 billion.
This signals to the venture market that after Anthropic's reporting, both companies will be valued relative to each other, and these numbers will set benchmarks for the entire generative AI segment.
AI Infrastructure: Mega Rounds and Revenues Above $1 Billion
The third week of October was marked by large infrastructure deals. Investors are increasingly distinguishing between applied AI and the "picks and shovels" — computing platforms with proven revenues.
- Modal Labs — D Series round of $750 million led by Accel at a valuation of $15.75 billion; the company's annual revenue surpassed $1 billion.
- Nscale — convertible round of $3.4 billion led by Third Point Ventures, the largest deal of the month.
- Verda — the Finnish GPU cloud provider raised $189 million in Series B led by Emergence Capital at a valuation exceeding $1 billion; annual revenue stands at about $165 million with positive cash flow.
- Salience Labs — $125 million in Series B for photonic computing.
New Unicorns and Applied Artificial Intelligence
Despite the capital concentration among leaders, applied startups continue to secure funding — provided they tackle costly corporate challenges.
Early Week Deals
- Town — $108 million at a $1 billion valuation: the company develops AI assistants capable of functioning at the level of entire teams.
- Dream Labs — former NVIDIA researchers raised $90 million to create a universal AI "brain" for affordable robots.
- Legora — $550 million in Series D at a $5.55 billion valuation; legal AI has established itself as one of the strongest verticals of 2026.
- Plinto — €2.9 million pre-seed for AI agents to check invoice errors.
Defense Technologies and Cybersecurity
Defense tech has officially transitioned from a niche segment to the mainstream of venture capital. Shield AI secured $1.5 billion in Series G at a valuation of $12.7 billion, while Anduril conducted an employee tender for $1.3 billion, during which the company's valuation rose from $61 billion to $90 billion in just five months.
In cybersecurity, Armadin stands out: $255 million in Series B led by Andreessen Horowitz and Accel at a valuation of $2.5 billion for its autonomous offensive security platform. Investors are betting on protection against AI-augmented attacks.
Fintech: 35% Growth and Tokenization
The fintech segment is experiencing a strong recovery. Global investments in the sector in Q3 2026 amounted to approximately $27.5 billion across 897 deals — a 35% increase compared to the previous year.
- Ramp — $1.85 billion at a $60 billion valuation, one of the largest fintech rounds of the year.
- Valon — $150 million in Series D at a $2.3 billion valuation involving Ribbit Capital.
- Spiko — $90 million in Series B led by NEA for scaling tokenized money market funds.
- Capitolis — $120 million in Series E.
Cryptocurrency venture remains cautious: in the first 18 days of October, crypto projects raised approximately $437 million across 27 rounds, with the bulk provided by Strive's post-IPO round of $208 million.
Deep Tech, Biotech, and Climate Technologies
Venture funds continue to diversify portfolios beyond AI applications:
- Oratomic — $475 million in Series B from a syndicate including ARCH Venture Partners, Khosla Ventures, Index Ventures, General Catalyst, and Bezos Expeditions.
- OMass Therapeutics — $310 million in Series C; Soufflé Therapeutics — $135 million in Series B for RNA therapy.
- Voltus — oversubscribed Series D round of $225 million for a distributed energy platform.
- Icon — $200 million in Series D for robotic construction with participation from Baillie Gifford and BlackRock.
New Venture Funds and Dry Powder
Fundraising continues, albeit concentrated among a limited number of managers. Among notable funds in recent weeks:
- Diffusion ONE — $1.25 billion;
- DCVC VII — approximately $654 million;
- TCGX Asia Life Sciences Fund I — $600 million;
- PSV Tech Fund II — $56 million for pre-seed startups in Northern Europe.
The IPO Market and Valuation Risks
2026 has already become a record year for tech listings; however, October's volatility has led some issuers to pause their listings. Companies in the Philadelphia semiconductor index have lost over $1.6 trillion in market capitalization in less than two weeks, and CoreWeave's bonds, with around $50 billion in debt, have sharply declined in value. AirTrunk REIT, Firmus, and SB Energy have postponed or withdrawn their offerings, while bankers note that several companies are waiting for the outcome of Anthropic's listing.
Asia Remains Active
In India, the debut of Zetwerk Manufacturing and Tonbo Imaging is expected this week, confirming the resilience of the exit window in emerging markets.
Russia and the CIS: The Market Searching for a Bottom
The Russian venture market remains under pressure. For the first half of 2026, the investment volume in tech startups was approximately $29.3 million — a 62% decrease compared to the previous year, and the number of deals fell to 35. Meanwhile, capital is shifting toward M&A deals: 33 transactions totaling around $829 million. Investors prefer mature companies with proven business models and industrial B2B technologies.
Conclusions for Investors
The startup and venture investment market in October 2026 exhibits a two-speed dynamic. Capital is concentrating in leaders — AI labs, infrastructure, and defense technologies — while other companies must prove revenue and unit economics. The key benchmarks for the coming weeks are:
- the results of OpenAI's round and its final valuation;
- the parameters and market reaction to Anthropic's IPO;
- the dynamics of semiconductor stocks and AI infrastructure debt market;
- the pace of new venture fund raises by the end of the year.
For funds, this is a period when discipline in valuations and diversification across sectors become more important than the speed of deal entry.