Oil Market: Brent Hits Five-Month High
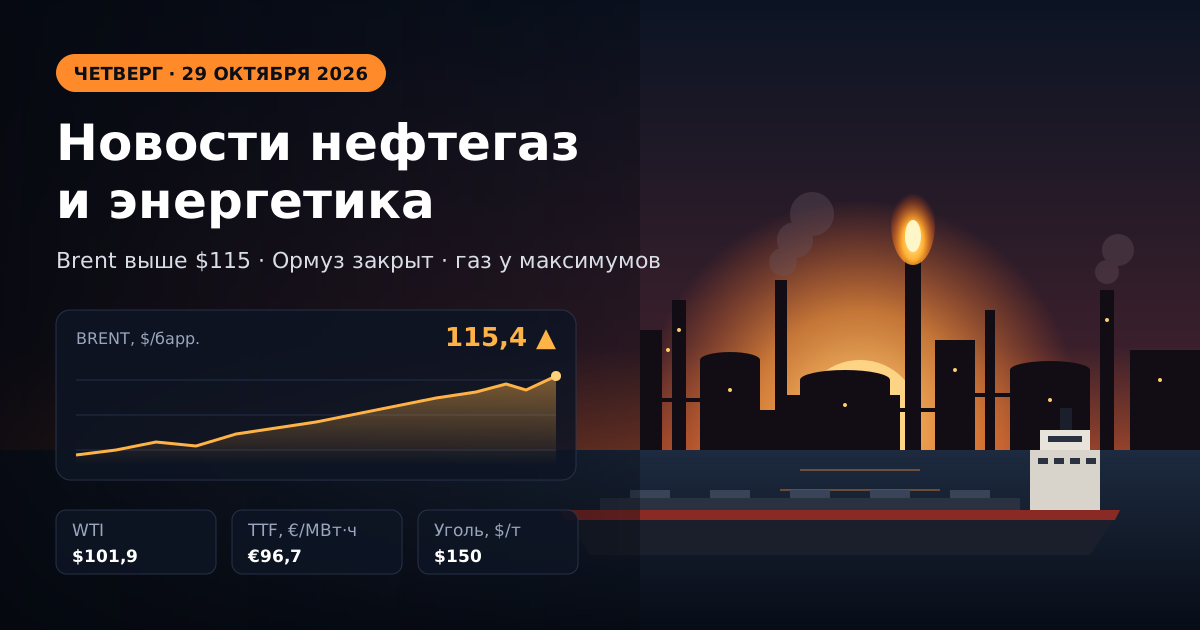
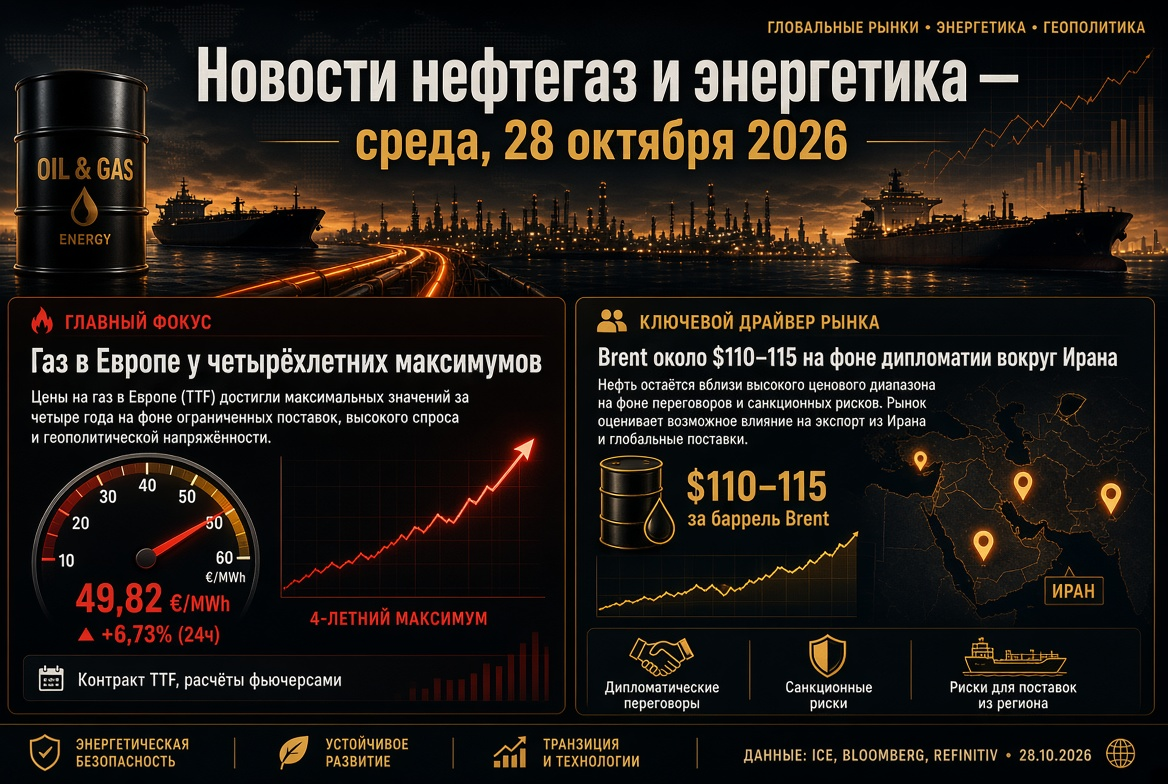
December futures for Brent traded in the range of $109–111 per barrel on Tuesday. The November contract for WTI hovered around $99–100. Since early October, oil prices have increased by approximately 10%, with Brent priced at around $100 on the first of the month. Oil prices are influenced by three main factors:
- Geopolitical Premium. Traders are factoring in the risk of supply disruptions from the Persian Gulf and the Red Sea into the pricing.
- Declining Inventories. According to the EIA, U.S. commercial oil inventories declined by 8.6 million barrels in the week ending October 9, down to 415.6 million barrels. Distillate stocks fell to 102.6 million barrels, approximately 12% below the five-year average.
- Conflicting Flow Estimates. U.S. Energy Secretary Chris Wright states that oil shipments from the Persian Gulf have recovered to about 80% of pre-war levels. However, vessel tracking analysts noted a sharp decline in transit through the Strait of Hormuz last week.
Middle East: Strikes on Saudi Aramco and Threats to Shipping
The main topic of the day for the oil market is the widening conflict within Saudi Arabia. The Houthis have claimed responsibility for attacks on Saudi Aramco facilities in Yanbu on the Red Sea coast, the Shaybah oil field, airports in Riyadh and Abha, as well as military facilities. Previously, the Aramco headquarters in Dhahran was also targeted. Riyadh has postponed the FII investment forum to next year.
The situation in the maritime corridor is also deteriorating:
- In the past two weeks, at least 18 vessels have been attacked;
- A tanker struck a sea mine in the southern part of the Strait of Hormuz;
- The average daily oil transit through the region last week dropped to approximately 8.5 million barrels compared to over 20 million the previous week.
This situation signifies high volatility in the market; any confirmation of damage to Aramco’s production or export facilities could quickly add several dollars to prices.
OPEC+ and IEA: Quotas on Hold, Shortage Until Year-End
Seven key OPEC+ members kept their production targets for November unchanged. Saudi Arabia's quota stands at 10.5 million barrels per day, Russia's at 9.9 million, and Iraq's at 4.4 million. The increases agreed upon for 2026 largely remain on paper. In August, the group produced approximately 25 million barrels per day, about 5 million below pre-war levels. The next meeting of the alliance is scheduled for November 1.
Key takeaways from the IEA's October report include:
- The global demand for oil in 2026 is projected to decline by 2.6 million barrels per day.
- Global supply in 2026 is expected to decrease by 5.8 million barrels per day.
- The market balance will remain in deficit until the end of the year.
- Shortages of middle distillates will continue through 2027.
Oil Products and Refineries: Diesel Remains the Most Scarce Link
The oil products segment is experiencing dual shocks: disruptions in fuel exports from the Middle East coincided with damage to refineries in Russia. The IEA approved the release of more than 20 million barrels of diesel from reserves. In total, around 330 million barrels have already been allocated to the market as part of the crisis plan. Global diesel exports in September were approximately 700,000 barrels per day lower than last year's figures. U.S. refineries are operating at around 93.5% capacity, sustaining high refining margins and profits for independent refiners.
Russia: Urals Discount Widens, Infrastructure Under Threat
Russian oil exports are facing pressure from multiple fronts:
- Competition for Markets. The discount on Urals in Baltic ports against Dated Brent has widened to $20.85 per barrel. This is due to weakening demand in India amid the return of Middle Eastern volumes and costly freight. Urals shipments from the Baltic have shrunk by 21.9% over the week.
- High Tax Base. The price of Urals used for calculating mineral extraction tax (MET) in October stands at about $104.7 per barrel compared to $92 in September. This is significantly above the budget target of $59.
- Logistics Attacks. On October 18, drones attacked the St. Petersburg oil terminal with a capacity of 12.5 million tonnes per year and the "Ruchyi" oil depot.
- Domestic Market Regulations. The ban on gasoline exports is in effect until January 31, 2027. Diesel export restrictions for producers have been extended until the end of October. Data on refinery loadings is classified under a decree dated September 28.
Gas and LNG: Europe Enters Winter with Storage Deficits
The Dutch TTF hub is trading around €88 per MWh. Since the beginning of the year, the price has more than tripled. Gas underground storage facilities in the EU are approximately 74% full, whereas the average norm for mid-October is about 86%. The market is further supported by three factors:
- Absence of Qatari LNG in the global market;
- Unplanned downtime in the Norwegian gas processing plant Kårstø;
- The EU's upcoming ban on imports of Russian LNG starting in January.
The primary supplier, compensating for the missing volumes, has become American LNG exporters. However, Europe is forced to compete for every cargo with Asian buyers.
Coal: Renaissance Amid Gas Crisis
Energy coal has once again become a safety fuel for the energy systems of Asia. The Australian benchmark Newcastle remains around $150 per tonne. This is approximately 40% higher than the beginning of the year and 45% above last year’s levels. On October 6, prices reached $152.2, the highest since October 2024. An added risk for the industry comes from a ruling by the High Court of Australia: when approving the expansion of coal mines, regulators are now required to consider emissions from burning coal abroad. Mining companies warn that this may hinder investments.
Electricity and Renewables: Renewable Energy as a Price Buffer
The energy crisis has accelerated the development of renewables. In June, solar generation became the largest source of electricity in the EU for the first time, accounting for around 25% of output, or 52 TWh. In Germany, the share of renewable sources in the first half of the year reached 61.8%. According to the industry association SolarPower Europe, since the onset of the Middle Eastern crisis, solar energy has saved the European Union around €20 billion on gas imports. Auctions for onshore wind energy are oversubscribed: in Germany, 2.5 GW have been allocated at an average price of about €50.6 per MWh. Nevertheless, during the winter, with low solar generation, electricity prices in Europe will once again be tied to expensive gas.
What to Watch for Energy Sector Participants on Wednesday, October 21
- EIA Weekly Report on U.S. Oil and Oil Product Inventories. Particular attention should be paid to distillates and refinery loadings.
- Reports from Saudi Aramco and the Saudi Ministry of Energy. It will be important to confirm damage in Yanbu and Shaybah.
- Data on tanker transit through the Strait of Hormuz and freight rates.
- TTF dynamics and gas injection rates into European UGS facilities.
- Russia's government decision on diesel exports starting in November.
- OPEC+ signals ahead of the November 1 meeting and the status of the production capacity audit.
Overall, the global oil and gas market remains a seller's market: fundamental shortages are exacerbated by geopolitics, and oil product inventories are declining. For investors, this means sustained high volatility in the coming weeks. The most stable positions are currently observed among refiners, LNG exporters, and coal mining companies.