The Main Topic of the Day: Oil Market Between Record Deficit and Hopes for "Hormuz Truce"
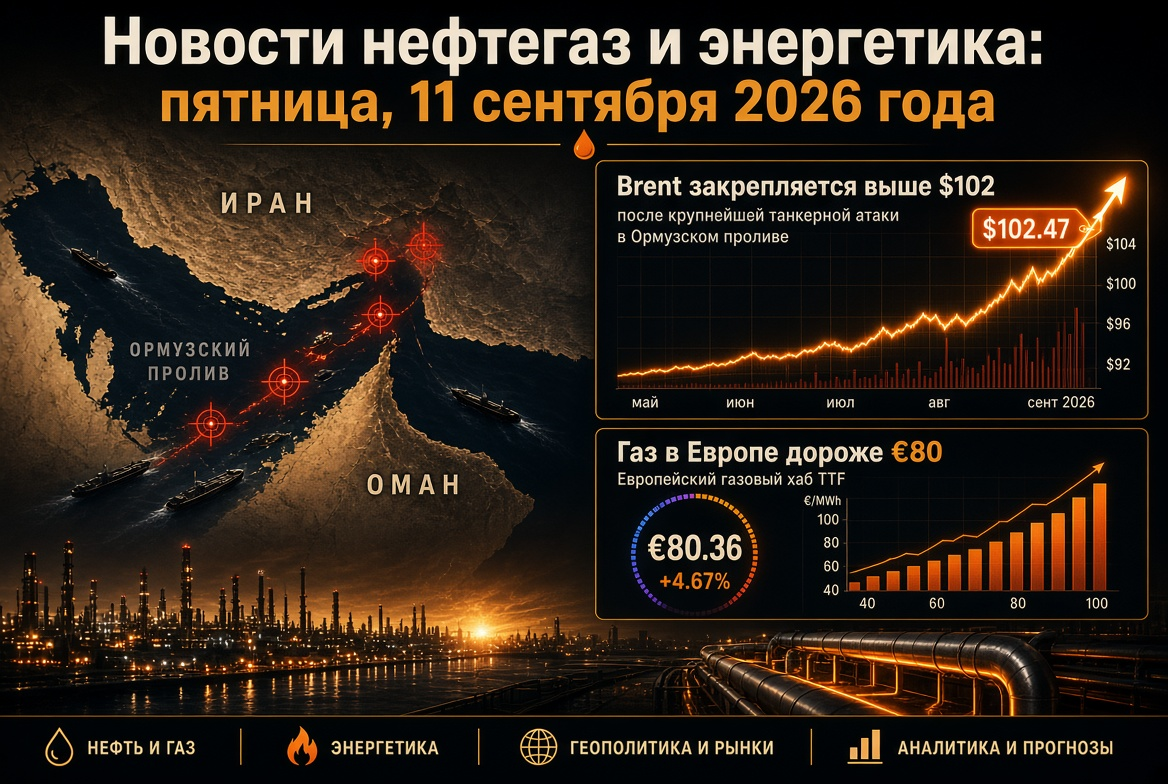
Oil prices at the week's close reflect two opposing factors. On one hand, the largest series of attacks on vessels since the start of the war: after the destruction of five Iranian tankers by American forces, Tehran attacked ten vessels near the Strait of Hormuz, and the IRGC has promised to escalate its response to any new strikes. On the other hand, the Financial Times reported that regional diplomats are attempting to develop a temporary agreement for managing shipping in the strait, which immediately eased some geopolitical premiums.
The physical picture remains grim:
- Transit through Hormuz: Only seven vessels passed through the strait on Thursday compared to eleven the day before and an average of around 15 over the past ten days; prior to the war, about 130 vessels passed daily.
- Saudi Production: In August, production decreased by approximately 1.9 million barrels per day to 6.24 million barrels per day — the lowest since 1990.
- Second Front in the Red Sea: The Houthis took control of the Yemeni port of Mocha on Thursday, and a series of strikes on facilities in Jazan, Najran, and Abha led to the shutdown of several oil facilities and injuries to 73 people.
Oil: Price Benchmarks and Forecasts After a Week of Growth
Closing Prices of the Week
- Brent: Approximately $103–104 per barrel on Friday after an intraday high above $108 on Thursday; weekly gain over 7%, with the yearly peak of $126.41 (April 30) remaining the upper benchmark.
- WTI: Approximately $99 per barrel after a brief consolidation above $100.
- U.S. Stocks: Commercial oil inventories decreased by 0.3 million barrels in the week ending September 4; the U.S. Department of Energy has raised its 2027 production forecast to 14.3 million barrels per day.
Revised Bank Forecasts
- Commerzbank raised its year-end Brent forecast to $85 (from $75), jet fuel to $1230 per ton, and diesel to $1200 per ton.
- Goldman Sachs expects $85 for Brent in December 2026 and $80 in 2027, but allows for a rise above $120 if Gulf production remains 4 million barrels per day below pre-war levels.
- Analysts at UBS and KCM Trade see risks tilted upwards amid high volatility.
IEA and OPEC: Two Views on the Global Oil Market Balance
The Friday report from the IEA was the harshest since the beginning of the conflict. The agency expects global oil demand to fall by 2.5 million barrels per day in 2026 — the largest annual decrease since the pandemic of 2020 — and a decline in global supply by 5.7 million barrels per day, or about 6% by 2025. Global stocks fell at a record pace in August — by 3.1 million barrels per day, while the global oil refining system, as the agency put it, is "operating at the limit." The return to surplus has been postponed until 2027.
OPEC, on the other hand, lowered its demand growth estimate for 2026 for the fifth consecutive month — to 380 thousand barrels per day with total consumption of 105.84 million barrels per day — but unlike the IEA, does not foresee an absolute decline. For 2027, the cartel raised its forecast: a growth of 2.36 million barrels per day to 108.19 million barrels per day, primarily due to China, India, and the rest of Asia. The discrepancy between the two institutions — over 2.8 million barrels per day for the current year — reflects the level of uncertainty in which oil companies and traders operate.
Refined Products and Refineries: Diesel as the Tightest Segment of the Global Energy Market
The refined product market is outpacing crude oil in terms of price increases. The average retail price of diesel in the U.S. has exceeded $6 per gallon for the first time, while crack spreads for middle distillates remain at multi-year highs. The reasons include a double blow to global refining:
- Restrictions on crude oil exports from the Persian Gulf and the shutdown of the 400 thousand barrels per day refinery in Jazan following attacks from Yemen;
- The Ukrainian campaign of strikes on Russian refineries — over 70 attacks since the beginning of 2026, with refining in Russia dropping to its lowest in two decades.
Russia has extended its ban on diesel exports until September 30 (with discussions ongoing about an extension until the end of the year), while the ban on gasoline exports is effective until January 31, 2027, and on aviation fuel until the end of November. Moscow is importing fuel for the first time in decades and has arranged for crude oil refining at a private refinery in Kazakhstan. Meanwhile, China will increase retail price ceilings on gasoline and diesel by 260 and 250 yuan per ton, respectively, from September 12 — a signal that the price shock has also reached regulated markets in Asia.
Gas and LNG: Europe Enters Winter with TTF Above €80 and Storage at 67%
The European benchmark TTF adjusted to €80.75 per MWh on Friday (a decrease of 1.6%), remaining near the highs since December 2022. The price has risen by 32% over the month and 147% year-on-year. The blockade of Hormuz has cut about 20% of global LNG flows, primarily from Qatar, while European gas storage facilities are only about 67% full against a seasonal norm above 80%. QatarEnergy maintains a target of restoring 50% capacity within a month after navigation normalizes, but without safe tanker passage, this remains a declaration. Amid this, two ECB representatives indicated on Friday that further rate hikes may occur if energy inflation continues to spread to other prices in the eurozone — a factor that limits speculative demand for commodities.
Coal: Twelve-Week High Amid Gas Switch
Newcastle thermal coal traded around $148 per ton on September 10 — a twelve-week high, with a 14.5% increase over the month and nearly 47% year-on-year. The shortage of LNG is driving coal generation in Northeast Asia and parts of Europe, while global electricity consumption, fueled by data centers and air conditioning, is slowing down coal displacement. The paradox of the moment: China officially reported that solar power has surpassed coal for the first time in installed capacity, but in terms of actual generation, coal remains the largest source of electricity in the world.
Electricity and Renewables: Structural Trend Against Short-Term Chaos
The energy transition remains the only predictable vector in the sector. China leads in investments, patents, and exports of clean technologies, India is building renewable capacities faster than it can utilize them, and Europe is experiencing an excess of solar and wind generation while lacking storage, leading to increasingly negative electricity prices during the day. Every euro increase in TTF strengthens the economics of battery storage, grid investments, and long-term contracts for "green" energy. The corporate sector is restructuring portfolios: Shell sold a gas power plant in the U.S. for $715 million, while Enbridge is acquiring Tallgrass's pipeline business for $2.55 billion, betting on oil transportation infrastructure.
Logistics and Freight: Tankers as a New Bottleneck
Even with available physical volumes, oil exports from the Gulf are limited by a shortage of ships. The freight rate for VLCCs on the Middle East to China route has reached a record nearly $800,000 per day, and transport from the U.S. Gulf to Asia costs $29.5 million per trip, excluding military risks. The redirection of Saudi shipments through the Red Sea and Mediterranean increases transit times by 30 days and strains the fleet, exacerbating the tonnage shortage for all exporters.
What Energy Market Participants Should Watch Over the Weekend
- Any confirmations or denials regarding a temporary shipping agreement in the Strait of Hormuz and Tehran's reaction.
- Statements from the coalition regarding Yemen after the Mocha takeover and the condition of the Yanbu terminal — the last major bypass for Saudi oil.
- The dynamics of injections into European gas storage facilities and the JKM–TTF spread as an indicator of competition for spot LNG.
- Signals from the Fed and ECB: a tightening of rhetoric could cool the commodity rally regardless of geopolitics.
- Decisions from Russian regulators regarding export restrictions and fuel imports prior to the heating season.
Conclusions and Risks for Investors and Energy Sector Companies
- Oil. The $100 mark has solidified as support; a diplomatic breakthrough in Hormuz could swiftly push Brent to $85–90, while new attacks on vessels open the way to $115–120.
- Refined Products and Refineries. Middle distillates remain the most scarce segment; refiners' margins outside conflict zones are at historical highs, with retail prices exerting political pressure from the U.S. to China.
- Gas. Europe enters the heating season with historically low reserves; TTF above €90–100 with a cold winter is the base, not stress scenario.
- Coal. Increased demand in Asia and Europe will persist at least until Qatari LNG supply is restored.
- Renewables and Electricity. Capital is flowing into solar and wind generation, storage, and grids at an accelerated pace, but short-term stability in energy systems still relies on gas and coal.
The week's outcome for the global oil and gas and energy sectors: the market has received a hint of a diplomatic exit from the Hormuz stalemate for the first time in months, but physical indicators — from record diesel prices to Saudi production at its lowest since 1990 — suggest that supply shortages will dictate the prices of oil, gas, and electricity for many weeks to come. Scenario planning, logistical diversification, and hedging discipline are critically important for participants in the energy market.