Current Startup and Venture Capital News as of September 12, 2026: Mega Rounds in Infrastructure, AI Chips and Defense Technologies, IPO Preparations for DeepSeek and Oura, Strategic Deals by Meta and Salesforce, as well as Signals for Investors and Funds.
The second week of September 2026 has illustrated the true direction of venture capital. In just one day, the ten largest deals generated approximately $4.8 billion, with 93% of this amount going to just three companies — The Boring Company, Positron AI, and Mach Industries. The market did not become "broadly risky": investors are willing to issue giant checks only to those startups that control a scarce resource — tunnels, inference chips, optical connections for data centers, or defense manufacturing.
Key events shaping the venture market agenda for Saturday, September 12, 2026:
- The Boring Company closed a $3 billion Series D round at a $23 billion valuation, with the UAE as the lead investor, accompanied by a contract to build over 150 km of tunnels.
- Positron AI raised $875 million at a $5 billion valuation just seven months after a round at $1.06 billion.
- Mach Industries expanded its Series C by an additional $600 million; the defense startup's valuation doubled to $3.7 billion within three months.
- Harvey secured $550 million at a $15.5 billion valuation, reinforcing the thesis of vertical AI as a distinct category.
- DeepSeek hired CITIC Securities to prepare for an IPO on the Shanghai STAR Market at a potential valuation of around $75 billion.
- Meta and Salesforce are acquiring AI teams: Stilla.ai is already within Meta's perimeter, while Listen Labs is in discussions for ~$2 billion.
The Boring Company: $3 billion and Sovereign Capital as a Market Entry Strategy
The largest deal of the week is The Boring Company's Series D round of $3 billion at a $23 billion valuation. The lead investor was the United Arab Emirates, alongside co-investors Sequoia Capital, Andreessen Horowitz, and Baron Capital. Importantly, the funding came with an agreement for the construction of over 150 km of tunnels in the UAE.
For venture investors, this represents a new format: sovereign capital serves both as a shareholder and anchor client, alleviating the company’s risk of customer acquisition. However, engineering and design risks remain — the primary operational showcase of the company continues to be the Vegas Loop, while projects in Los Angeles, Washington, and Chicago have been shelved. Nevertheless, the $23 billion valuation establishes a new norm: infrastructure startups with technology, political access, and the ability to participate in tenders over dozens of kilometers are receiving venture multipliers.
AI Infrastructure: Inference and Photonics Instead of Another Chatbot
The focus of venture investments in artificial intelligence has definitively shifted from models to the hardware that supports them.
Positron AI: $875 million as an Alternative to Nvidia in Inference
The startup from Reno, Nevada, closed its Series C at $375 million and Series C-1 up to $500 million at a $5 billion valuation. The round was led by NEA, Atreides Management, Valor Equity Partners, Andra Capital, SemiAnalysis Capital, and Jim Clark; the deal included participation from Qatar Investment Authority, Cisco Investments, and Naver Ventures. The Asimov processor employs a “memory-first” architecture with up to 2.3 TB per chip, with mass production slated for the second half of 2027. Over 50 racks of the previous generation have already been deployed in Oracle Cloud Infrastructure.
Ayar Labs: Optical Connections at $5 Billion
The developer of silicon photonics added $150 million to its March Series E, bringing the round total to $650 million and the valuation to approximately $5 billion, up from $3.8 billion at the beginning of the year. Strategic investors include Nvidia, AMD, and MediaTek. Demand from public companies underscores the thesis: Oracle reported quarterly capital expenditures of $28.5 billion, while hyperscalers issued bonds worth about $220 billion over the year to finance data centers.
Defense Technologies: Mach Industries Doubles Valuation in a Quarter
Mach Industries raised an additional $600 million in an expansion of its Series C, increasing the total round amount to ~$900 million. The valuation rose from $1.8 billion in June to $3.7 billion. Investors included Ribbit Capital, Infinite Capital, Bedrock Capital, and Sequoia. The company manufactures vertical takeoff drones, long-range strike systems, and counter-drone solutions, and is expanding into propulsion systems through the acquisition of Exquadrum.
Investors are financing not just a standalone platform but an industrial base: vertical integration of production is becoming a key barrier to entry. The defense sector in 2026 has definitively ceased to be a niche venture category — Anduril raised $5 billion in the first half of the year, while Finland's ICEYE secured $1.2 billion.
Applied AI: Premium for Process Ownership
Alongside the mega rounds in infrastructure, funding for vertical AI companies continues, with their protection stemming from integration into regulated processes:
- Harvey — $550 million at a $15.5 billion valuation (led by Diffusion and Lightspeed); the legal AI startup released its own Tenet model based on open weights.
- Inspiren — $70 million Series C at a $550 million valuation led by NewView Capital; AI monitoring in nursing homes.
- Rogo Technologies — around $30 million in strategic investments from Citi, Barclays, BNP Paribas, MUFG, and Société Générale; banks are becoming both shareholders and clients.
- Graph AI — $13.3 million from Insight Partners and Bessemer for pharmacovigilance automation.
The common denominator for these deals is a specific buyer, measurable operational outcomes, and a high cost of product replacement within the client's stack.
M&A and Strategic Deals: Corporations Acquire Teams, Regulators Watch
Meta acquired the Stockholm startup Stilla.ai, which emerged from stealth mode after a $5 million seed round, to enhance business agents in WhatsApp and Messenger. Salesforce is negotiating to acquire Listen Labs for around $2 billion — whereas the startup had just signed a term sheet for $125 million at a $1.5 billion valuation. This illustrates how AI companies are becoming targets for acquisition well before reaching traditional scale.
At the same time, the U.S. Department of Justice is reviewing Nvidia's licensing deal with Groq valued at $17–20 billion for possible antitrust violations. For investors in chip startups, this is an important signal: the "license plus team transition" model as an alternative to a notified merger may cease to be effective.
Asia: DeepSeek Prepares for IPO, Alibaba Valuates UniPat AI at $2.5 Billion
DeepSeek has enlisted CITIC Securities and three other underwriters to prepare for a listing on the Shanghai STAR Market; this process is expected to commence by the end of the year. Concurrently, the company is conducting a pre-IPO round at a valuation of around 500 billion yuan (approximately $75 billion) following a June round of $7.4 billion. Alibaba is leading a $300 million round in UniPat AI — a model evaluation and training platform — at a valuation of $2.5 billion; the deal includes Tencent and HSG. China is placing billion-dollar valuations on AI "tools" rather than just the models themselves. In India, Swish raised $24 million in Series B funding from Bertelsmann India Investments for ten-minute food delivery.
IPO Market: The Window is Open, but Selectively
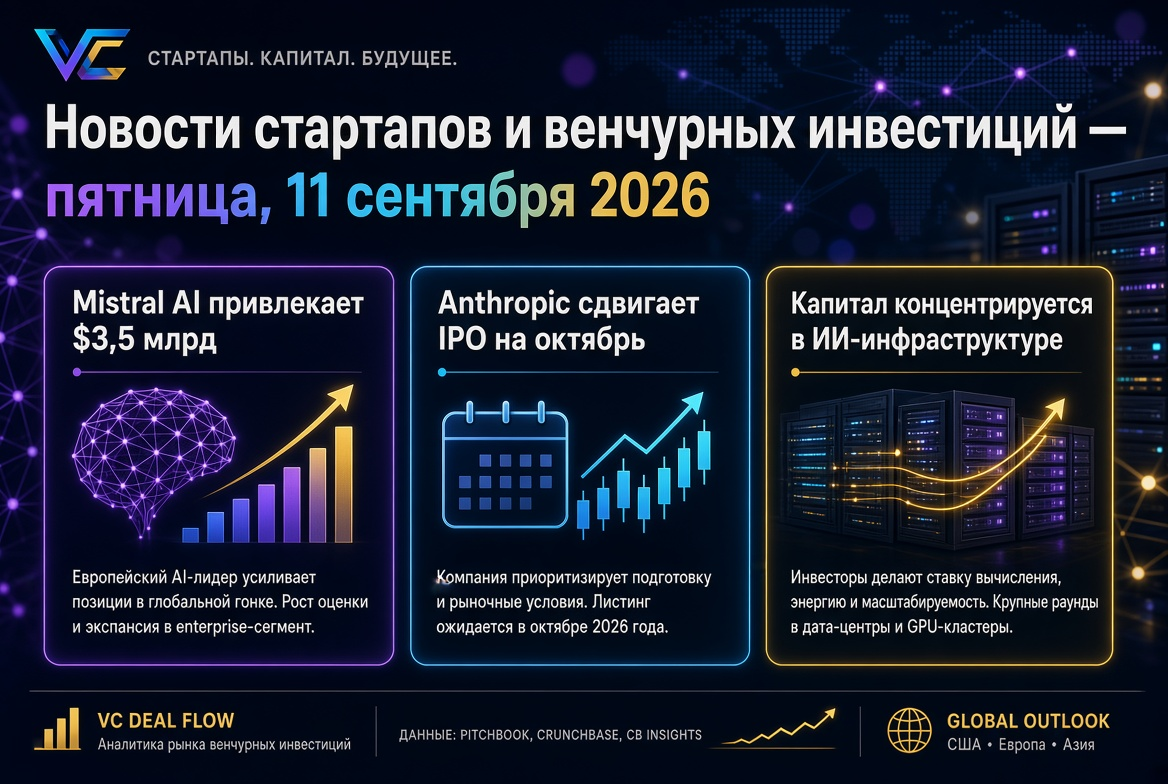
Oura has filed for a listing on Nasdaq under the ticker OURA and aims to raise up to $3 billion at a valuation exceeding $16 billion; the offering is expected by the end of September. Meanwhile, Motive Technologies has withdrawn its IPO of approximately $600 million — the public market continues to differentiate between "AI giants" and all others. Anthropic, as of mid-week, is pushing its listing to October. Direct listings are experiencing a record year in number but not in returns for investors.
Russia and the CIS: The Funnel has Narrowed
As of September 9, about 90% of Russian startups appear unprepared for investments: out of 2,681 applications for an industry showcase, only 2–4 projects made it to the final selection, with investors making offers totaling over 700 million rubles. The selection process is tightening — the market is increasingly filtering out projects without validated economics. The global context reinforces this trend: according to KPMG, global venture capital volume for the first half of 2026 reached $560.4 billion, but the top 10 deals accounted for nearly half of this amount, with approximately $217 billion attributed to OpenAI and Anthropic.
What This Means for Venture Investors and Funds
The September landscape fits into the formula "capital in excess, scarcity remains." Practical takeaways for managers include:
- Strategic capital becomes a distribution channel. The UAE for Boring, banks for Rogo, Oracle for Positron — an investor that is also a customer mitigates commercial risk more effectively than a higher valuation from a financial fund.
- Capital intensity is no longer a vice if it buys a barrier. Factories, chips, and photonics are financed in tranches against specific milestones: design, production of salable goods, customer qualification.
- "AI-powered" is not an investment thesis. Premiums are awarded to those who own regulated processes, data, and switching costs.
- The barbell market requires two strategies. Mega checks are concentrated in the U.S., while seed and early rounds in Europe, India, and China remain small and rigorously selected.
The venture market enters autumn 2026 with record capital reserves and a narrowing circle of recipients. Companies that cannot be replicated with the next model release are winning.