Oil Market: Brent and WTI Decline but Remain Above $100
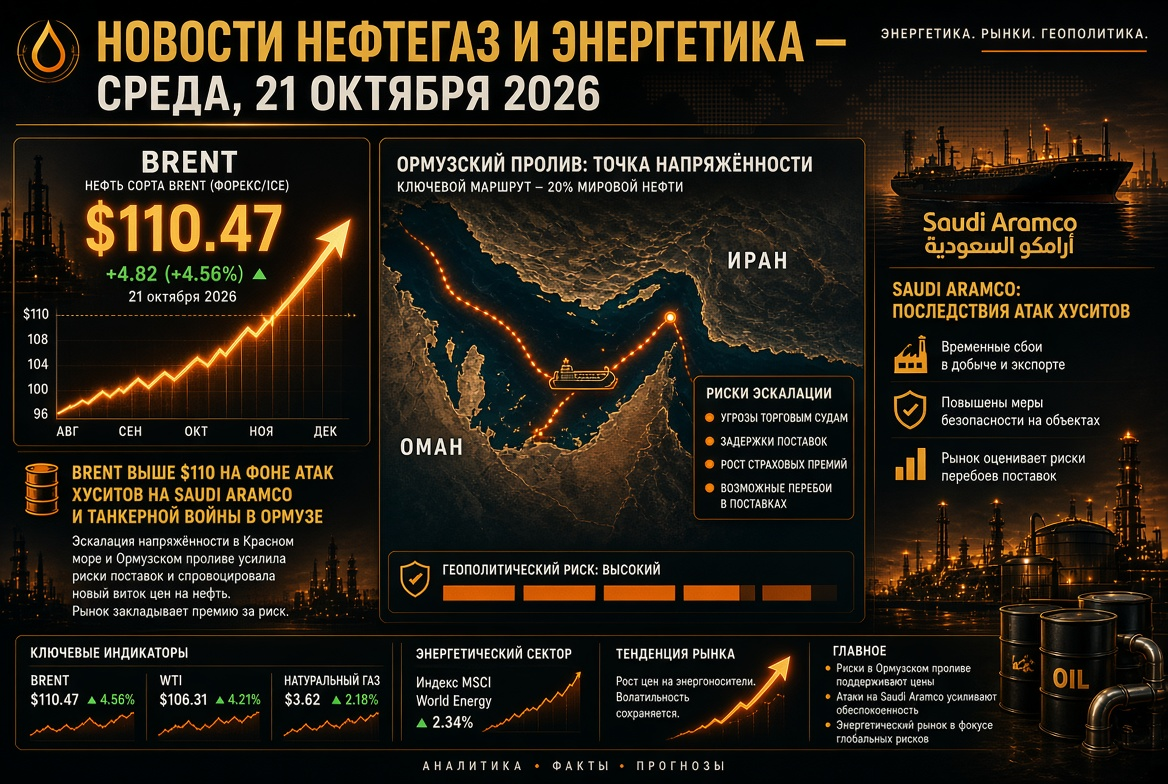
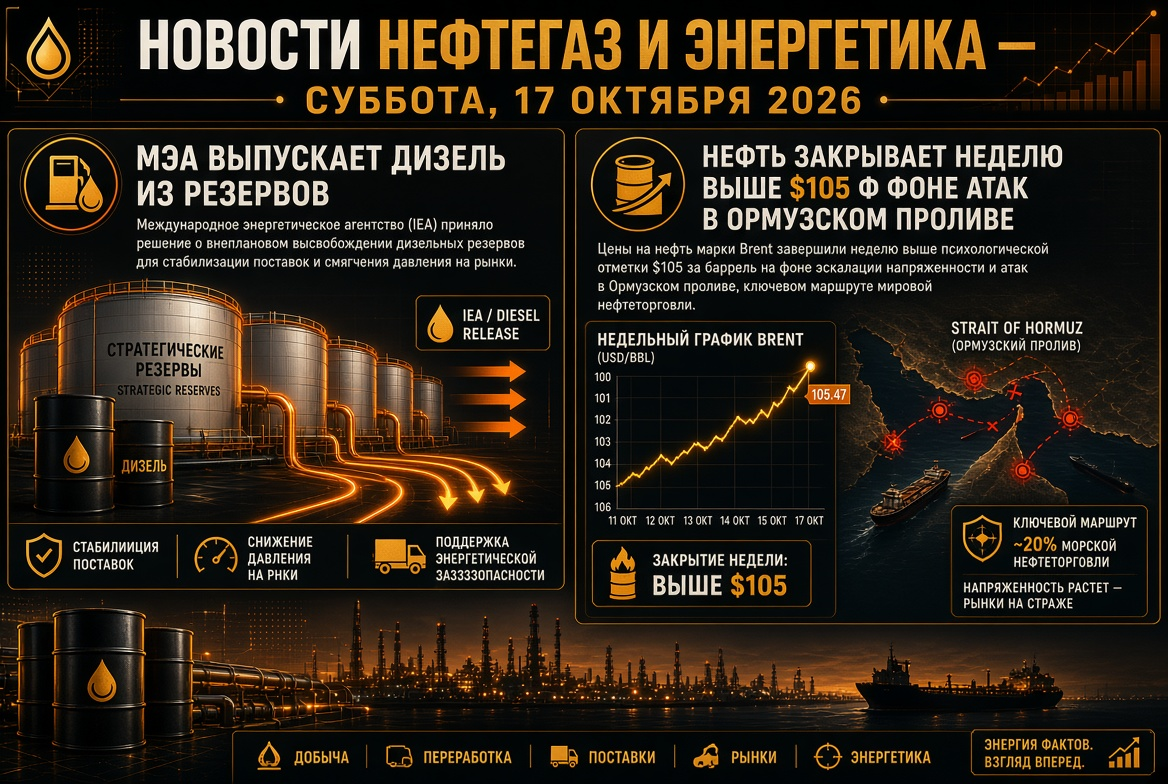
By Thursday evening, Brent was trading around $104 per barrel, while WTI hovered between $101 and $102. Earlier in the week, Brent had climbed to $109; over the past month, the benchmark has gained approximately 14% and over 50% compared to this time last year. Key drivers include:
- Saudi Arabia: The kingdom expects to restore about half of the East-West pipeline capacity damaged by drone attacks last week within a few days, reaching full capacity in approximately six weeks. This route, with a capacity of up to 7 million b/d, is the primary bypass for the Strait of Hormuz.
- Strait of Hormuz: According to the US Department of Energy, around 18 million barrels of oil and oil products flowed through the strait at the beginning of the week; Riyadh is ramping up shipments with support from US military forces.
- US Stocks: Commercial oil stocks fell by 0.64 million barrels to 423.4 million — below market expectations, although industry estimates prior indicated an increase of 7.1 million.
- Supply Risks: The Houthi advance towards the Bab-el-Mandeb Strait, the shutdown of several oil fields in Libya with the threat of force majeure, and Tehran's refusal to negotiate with Washington until its conditions are met.
Supply and Demand: OPEC and IEA Estimates
- Saudi Arabia reported to OPEC a production drop in August to 6.24 million b/d — the lowest since 1990; secondary sources estimate the level closer to 7.3 million b/d.
- The IEA has cut its global supply forecast for 2026 to 100.7 million b/d (–5.7 million b/d year-on-year).
- Global oil demand is projected to decrease by 2.5 million b/d in 2026, with a recovery of 2.6 million b/d in 2027.
- Observational global stocks decreased by another 95 million barrels in August; the cumulative reduction since February stands at 507 million barrels.
Refined Products and Refineries: Diesel is the Market's Main Shortage
The crisis is increasingly shifting from crude oil to refined products. Wholesale diesel prices in the US exceeded $200 per barrel at the beginning of September — nearly double pre-war levels, while the retail price reached a record $5.90 per gallon. In the EU, diesel costs around €2.04 per liter, close to the April record.
- Net diesel exports from Gulf countries in August were approximately 390,000 b/d — a quarter of pre-war volumes; total shipments from the Gulf and Russia are 1.6 million b/d lower than February levels.
- Global refining reached a summer peak of 81.4 million b/d, but a decline of 2.6 million b/d is expected by year-end.
- Refinery margins in the Atlantic Basin are at record levels; profitability in Singapore is suppressed by high freight costs.
For refineries outside the conflict zone, this is a period of super profits, while for fuel companies and consumers, it represents a shock of expenses.
Gas and LNG: Europe Enters Winter with Low Stocks
TTF futures dropped to €76–77 per MWh on Thursday after attempting to settle above €80; earlier in the week, prices approached €82 — a maximum since late 2022. Year-on-year, gas prices in Europe have risen by more than 130%. EU storage is only about 68% full — one of the lowest levels in two decades for this date. Pressures are being created by limited supplies of Qatari LNG, scheduled maintenance in Norway, and competition with Asia for cargoes. Henry Hub in the US remains around $2.90 per million Btu — a record spread is supporting US LNG exporters.
Geopolitics: Energy Truce Between Russia and Ukraine in Question
On 14 September, the US President announced that Moscow and Kyiv had agreed to cease strikes on energy facilities, attributing the rise in diesel prices primarily to this conflict. Kyiv reported that the agreement has not been finalized and is only possible with guarantees from partners; Turkey is acting as a mediator. Previous attempts at such truces have proven short-lived. If the truce comes into effect, the recovery of Russian oil refining could reduce the premium in distillates. The sanction regime remains unchanged.
Russia: Fuel Export Restrictions Remain in Place
- A ban on gasoline exports is in effect for all market participants until 31 January 2027.
- The ban on the export of diesel, marine fuels, and gas oils for producers has been extended until 30 September; the market is awaiting a decision for October.
- According to the IEA, over the past eight months Russian refineries have faced effective strikes on average every three days; since July, the country has begun to import petroleum products.
- The Urals discount to Brent has nearly disappeared amid reduced shipments and high demand in Asia.
Asia: China Outbids India for Russian Oil
Russian oil imports to India dropped by about 26% in August, to approximately 2.1 million b/d, down from a record 2.8 million b/d in July; total crude imports fell to 4.6 million b/d. Chinese refiners are aggressively purchasing cargoes, replacing volumes from the Middle East, while India partially offsets losses with Venezuelan oil. The raw material shortage at Indian refineries threatens a reduction in diesel and gasoline exports — an additional factor of tension in the Asian refined products market.
Electricity, Renewables, and Coal: Insurance and Structural Shift
- Coal: Energy coal in Newcastle is around $145 per ton (+12% month-on-month, +40% year-on-year). The LNG shortage adds about 70 million tons of demand in Asia in 2026; coal generation in Japan has increased by 11%. Major producers are not sanctioning new mines, considering the surge cyclical.
- Renewables: By the end of 2025, renewable sources surpassed coal in global electricity production for the first time (33.8% vs 33.0%), and in April 2026, wind and solar generated more electricity than gas for the first time (22% vs 20%). The installation of solar capacity in 2025 reached a record 647 GW.
Expensive imported gas strengthens the economics of renewables and storage, but in the short term, coal and nuclear sources provide the necessary balance for the energy systems.
Macroeconomics: Fed Responds to Oil Inflation
On 16 September, the Fed unanimously raised the rate by 25 basis points to 3.75–4.00% — the first increase since 2023 — signaling the possibility of another move by year-end. The regulator acknowledged that it cannot influence oil prices but intends to prevent inflation from spreading. The yield on 10-year US bonds stands at around 5%. For the energy sector, this signifies an increase in capital costs: capital-intensive projects in renewables, networks, and LNG are under pressure, while oil companies with strong cash flows appear more resilient.
What to Monitor for Investors and Energy Market Participants on Friday
- The pace of recovery of the East-West pipeline and shipments from Yanbu.
- Tanker traffic through the Strait of Hormuz and Bab-el-Mandeb.
- Confirmation of the energy truce between Moscow and Kyiv.
- Russia's decision on diesel exports after 30 September.
- TTF dynamics, the pace of injection into European gas storage, and the schedule of Norwegian maintenance.
- Weekly statistics on drilling activity in the US and diesel crack spreads.
The baseline scenario for the coming days is oil in the range of $100–110 per barrel, with heightened sensitivity to news from the Middle East. Refined products and gas remain the most strained segments of the global energy market.