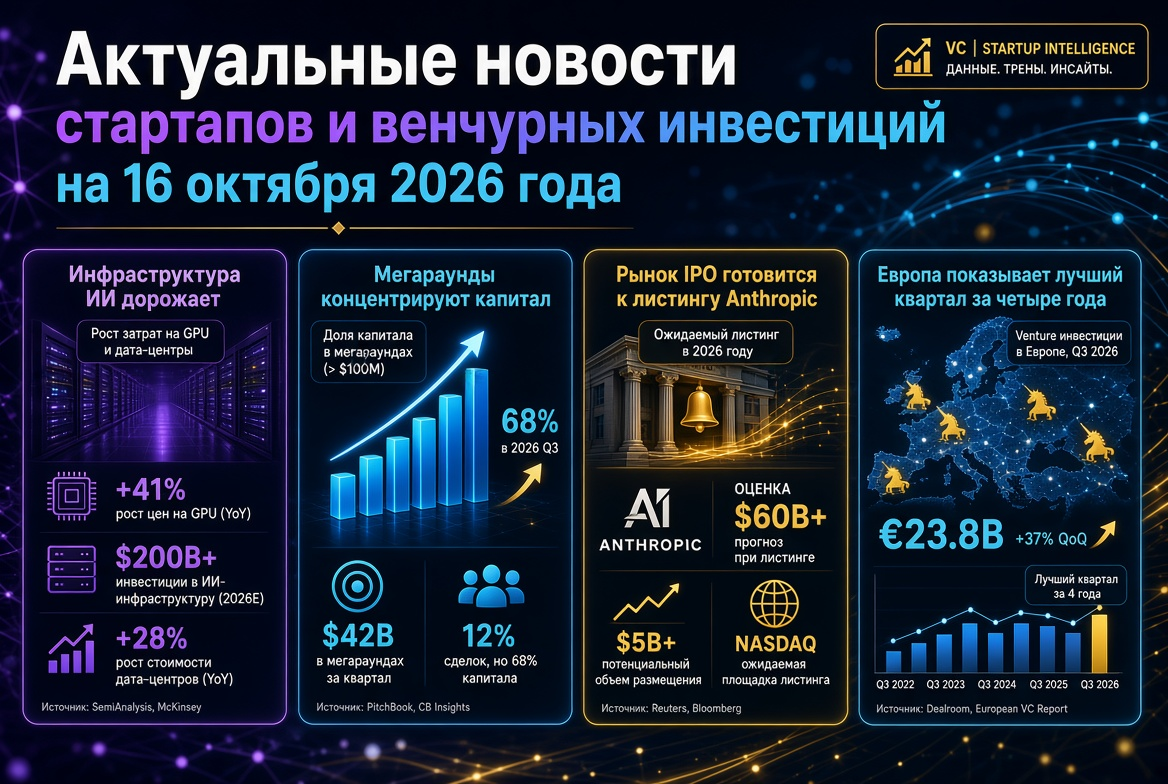
Venture Market in Mid-October 2026: Record Capital Volumes, High Concentration in AI, Biggest Rounds of the Week, IPO Preparations, and Signals for Funds and Investors
Venture investments in 2026 are on track to reach a historic record, yet the market is becoming increasingly uneven. Capital is being concentrated in a small group of companies related to artificial intelligence. The past week confirmed this trend: the largest rounds were raised by cloud AI infrastructure, fintech with AI products, and AI agent developers. Concurrently, the market is debating the quality of revenue for AI startups and the sustainability of infrastructure built on debt financing. Below are key events for venture investors and funds.
Macro Picture: A Record Year Amid Declining Quarterly Dynamics
According to Crunchbase, global venture investments in Q3 2026 amounted to $159 billion. Approximately 6,000 startups received funding. The quarterly volume decreased by 25% compared to Q2 ($212 billion), but increased by 53% year-over-year. Over the last nine months, startups have raised $679 billion, the highest for the corresponding period in the history of observations.
- AI Share: $102 billion, or 64% of global venture capital for the quarter.
- Mega Rounds: 27 companies raised rounds of $1 billion or more, a record high: there were 16 such companies in Q2 and 14 in Q1.
- Geography: US startups accounted for $91 billion (57%), with the San Francisco Bay Area representing 24% of the global volume.
- Stages: late-stage rounds reached $105 billion (+73% year-over-year), while early-stage rounds amounted to $40.6 billion (+25%).
American statistics from PitchBook and NVCA show the same trend. From January to September, the volume of venture deals in the US reached $515.8 billion, with 82.7% allocated to AI companies. Additionally, about 90% of the funds were directed towards rounds of $50 million or more. For startups outside of AI, the market record offers little expansion in access to funding.
Key Theme of the Week: AI Infrastructure Attracts Mega Rounds
The most notable deal of the week was the $750 million Series D round for California’s cloud platform Modal, with a post-money valuation of $15.75 billion. The round was led by Accel, with participation from Kleiner Perkins, Menlo Ventures, General Catalyst, Redpoint, Lux Capital, and others. The company stated that its annual revenue run rate exceeded $1 billion, and platform usage has tripled since May.
Investors are funding not only computing but also associated segments of the AI infrastructure:
- Salience Labs (Oxford) raised $125 million in a Series B round led by Bullhound Capital, with participation from AMD Ventures and Intel Capital. The company is developing optical switches for GPU clusters.
- Skeleton Technologies (Estonia) received strategic investments led by Siemens, reportedly exceeding $100 million. The company has become a “unicorn” and is building a supercapacitor manufacturing facility in the US for data centers.
- Labelbox announced Series E funding of over $100 million, including a credit line. The funds will be used for reinforcement learning tools and corporate AI agents.
- Tamr secured $21 million in growth investments from Volition Capital for managing corporate data for AI systems.
At the same time, the public market is sending a warning signal. On October 14, shares of AI cloud company CoreWeave plummeted amid concerns about borrowing costs and the sustainability of infrastructure expanded through debt. For venture funds, this serves as a reminder to differentiate between companies with proven demand and projects whose profitability depends on future capacity utilization.
Fintech: Ramp Increases in Value by $16 Billion in Four Months
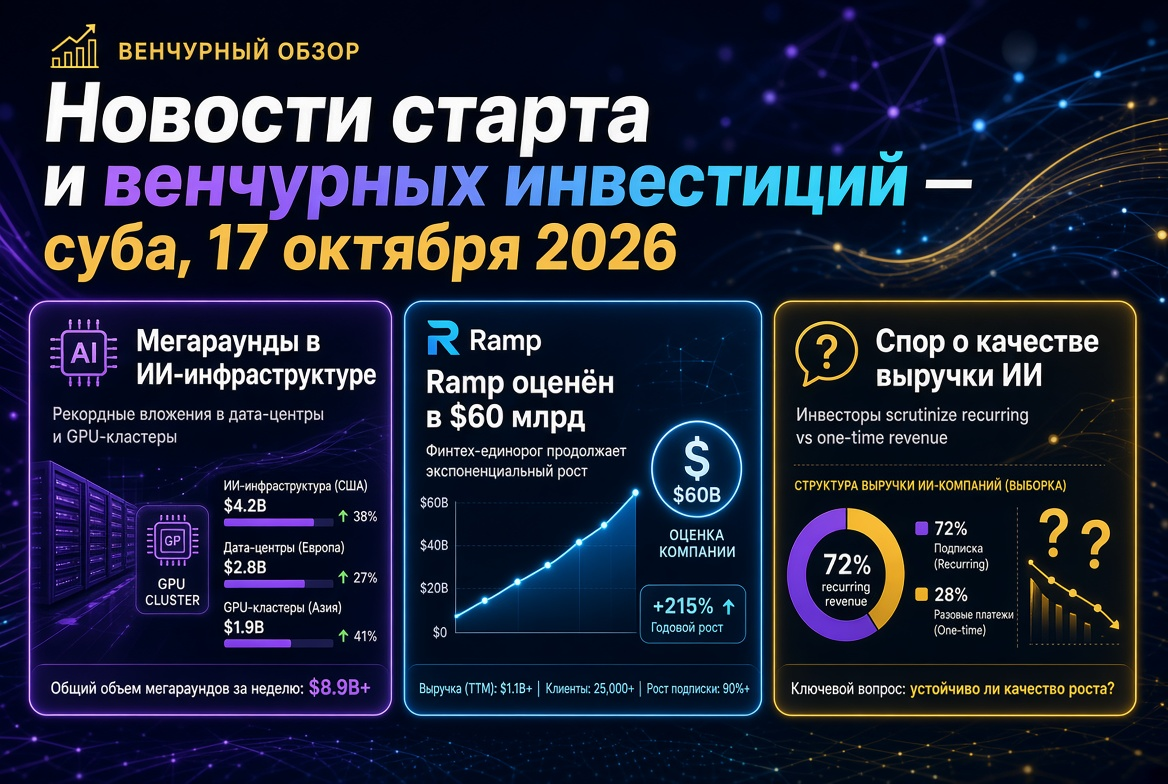
According to Bloomberg, fintech platform Ramp raised approximately $1.85 billion at a pre-investment valuation of around $60 billion. The round was led by Dragoneer and Thrive Capital, and Founders Fund contributed a significant investment. In June, the company raised $750 million at a $44 billion valuation. Ramp serves over 70,000 companies, and its annual revenue reportedly exceeded $1.5 billion as of the summer. The company has not commented on the round.
This deal underscores the consolidation of the corporate expense management segment. Ramp’s nearest competitor, Brex, was taken under the control of Capital One this year. Ramp is enhancing the AI component of its products, which directly supports its valuation.
AI Agents and Geopolitics: Manus Raises Over $500 Million
Butterfly Effect, the parent company of AI agent developer Manus, has closed a round of over $500 million. Co-investors included Boyu Capital and IDG Capital, with participation from Tencent, HSG, and ZhenFund. This is the first financing since Beijing forced Meta to cancel a deal to acquire Manus for over $2 billion. The valuation remains undisclosed, although prior reports indicated negotiations at around $4 billion.
The Manus case demonstrates that regulatory risk in cross-border AI deals has become a distinct aspect of due diligence. Investors need to consider not only the technology but also jurisdiction, capital structure, and the potential for exit through strategic sales.
Deep Tech, Biotech, and Defense: Capital for Long Cycles
Beyond AI, venture funds continue to finance capital-intensive technologies with long payback horizons:
- OMass Therapeutics (Oxford) raised $310 million in an oversubscribed Series C round. The round was led by Bain Capital Life Sciences, Forbion, and Novo Holdings. The funds will be used for clinical research on drugs for endocrinology and immunology.
- Oratomic closed a Series B round of $475 million for the development of fault-tolerant quantum computers.
- Sabi raised $50 million in seed funding led by Khosla Ventures. The company is creating a wearable interface for “brain-AI” communication.
- Fortastra secured $30 million in a Series A round for maneuverable spacecraft designed to protect orbital infrastructure.
- Tessolve Semiconductor (India) received $75 million from Vector Line Capital for international expansion through acquisitions.
Funds and LPs: OrbiMed Raises $3 Billion
The funding side remains active. Specialist healthcare investor OrbiMed announced the raising of $3 billion across two funds. OrbiMed Private Investments X raised over $1.9 billion for venture deals in life sciences in the US and Europe. OrbiMed Asia Partners VI secured over $1 billion for growth and venture investments in Asia. In the US, according to PitchBook-NVCA, emerging managers have closed 81 first-time funds this year, accounting for $4.9 billion. The fundraising landscape still favors large, established teams for Limited Partners (LPs).
IPO Window: DayOne Files for IPO, Anthropic Clarifies Timeline
The public offering market remains a primary channel for venture funds to return capital. This week:
- Singapore-based AI data center operator DayOne Data Centers filed for an IPO on Nasdaq under the ticker DODC. The underwriters are Morgan Stanley, J.P. Morgan, BofA Securities, and Citigroup.
- According to media reports, Anthropic may start its roadshow in the week of November 9, approximately a month later than initially planned. The expected valuation is between $1.8 trillion and $2 trillion. The company has not officially confirmed the timeline.
- The case of SpaceX, the largest IPO in history (June 2026, valuation of $1.77 trillion), serves as a reminder of the volatility post-listing. Reports indicate that by the end of July, the company’s shares had lost about half of their peak value.
Russia and CIS: Market Contracts, Focus on Strategics
The Russian venture market is moving against the global trend. According to a report from the Moscow Venture Fund, in the first half of 2026, investors injected 4.6 billion rubles, nearly 48% lower year-on-year. The capital deficit is exacerbated by tight monetary policy. Investors are concentrating on robotics, IT, and artificial intelligence. The primary exit scenario remains the sale of a stake to a strategic investor rather than an IPO. The Moscow Venture Fund announced an allocation of 250 million rubles to technology companies and expects about 1 billion rubles in co-investments.
Risks and Conclusions for Venture Investors
Chamath Palihapitiya, founder of Social Capital, pointed out the issue of "quality of revenue" in AI. He suggests that a significant portion of AI companies' revenues comes from other AI startups that themselves rely on venture funding. For venture funds, this leads to several practical conclusions:
- Distinguish Run-Rate from ARR. The annual revenue run rate in infrastructure with consumption-based billing is not equal to contractually recurring revenue.
- Analyze the Deal Structure. The headline amount of a round may include credit lines and secondary share sales.
- Consider Customer Concentration. Dependence on venture-funded AI companies creates a chain of mutual risks.
- Factor in Regulatory Risk. The Manus case demonstrates that an exit through sale may be blocked at the government level.
- Diversify Beyond AI. Biotech, quantum technology, defense, and industrial deep tech offer alternative sources of returns.
In conclusion, the global startup and venture investment market remains generous but is becoming increasingly selective. Capital is flowing to companies that control the infrastructure, data, and customer relationships necessary for the commercialization of AI. For funds, key selection criteria in Q4 2026 will become the quality of revenue, discipline in valuations, and realistic exit pathways.