The global energy sector concludes the week in a state of high volatility. Brent crude oil remains above $100 per barrel. Gas prices in Europe are trading at highs not seen since the end of 2022. The diesel market continues to be the most strained segment of the oil and gas industry. For investors, oil and fuel companies, traders, and refinery operators, three key themes remain paramount:
- attacks on tankers in the Strait of Hormuz;
- the diesel supply agreement between Russia and the US;
- the fate of strikes on refining infrastructure following the collapse of the "energy truce."
Oil Market: Brent at $104 Amid Expectations of Sanctions Easing Against the “Shadow Fleet”
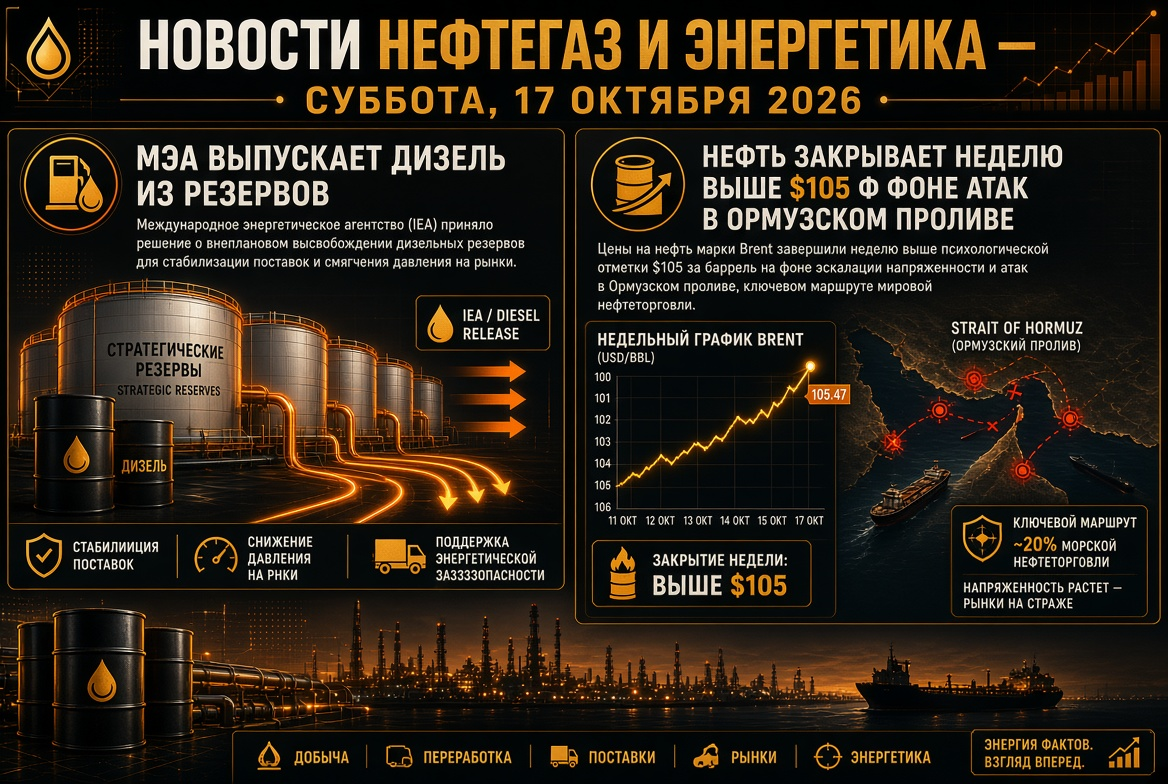
On Thursday, oil prices dropped by approximately 2%. The December futures for Brent fell to around $103.5–104 per barrel after closing the previous day at $106.06. November WTI is trading around $94–95. Price pressures were exerted by reports that the US administration is considering easing sanctions against vessels of the “shadow fleet.” Washington's goal is to reduce record freight rates and accelerate oil exports from the Persian Gulf.
The fundamental support for the oil market remains intact:
- US inventories are declining. According to the American Petroleum Institute, commercial inventories fell by 11.1 million barrels in the week ending October 9.
- Prices remain high year-on-year. Brent is approximately 70% more expensive than a year ago, with an annual high of $120.88 recorded on April 30.
- Brent-WTI spread has widened. The difference exceeds $9 per barrel, reflecting a risk premium on sea routes.
Strait of Hormuz: The Most Dangerous Phase for Shipping Since the War Began
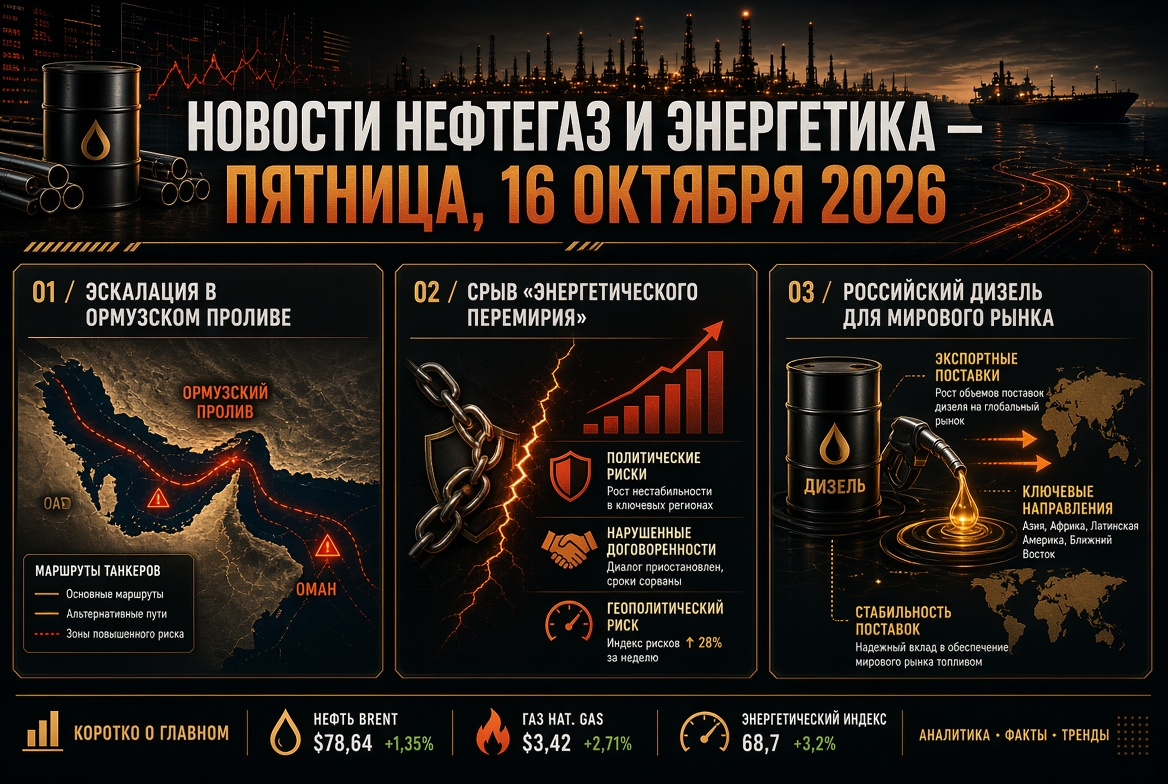
October has emerged as one of the most stressful months for the tanker fleet since the onset of the conflict surrounding Iran in late February. This week, two vessels sank, including the Singaporean container ship GFS Pride. Since the beginning of the week, there have been at least nine attacks near the strait, targeting tankers carrying oil, LNG, and liquefied petroleum gas.
- In September, crude oil exports from the Middle East nearly returned to pre-war levels, enabled by night passages of tankers under US Navy escort with transponders turned off.
- Iran is increasing pressure to regain control over flows, with transit times through the strait on certain days halving or more.
- For insurers and charter companies, this means maintaining record rates and military premiums.
OPEC+: Quotas Frozen, Actual Output Below Targets
At the meeting on October 4, seven key OPEC+ members kept quotas for November unchanged. The group includes Saudi Arabia, Russia, Iraq, Kuwait, Kazakhstan, Algeria, and Oman. Target levels stand at about 10.5 million barrels per day for Saudi Arabia, 9.9 million for Russia, and 4.4 million for Iraq.
- The actual output of the core alliance in August was approximately 25 million barrels per day, about 5 million barrels per day below pre-war levels.
- There remain approximately 2 million barrels per day in production cuts.
- The secretariat is completing an audit of maximum capacities, which will be used to calculate baseline levels for 2027.
- The next meeting is scheduled for November 1.
IEA Report: Oil and Diesel Shortages Will Persist Until 2027
The October report from the International Energy Agency confirms that the global oil market balance remains deficit.
- Global oil demand will decrease by 2.6 million barrels per day in 2026, down to 102.4 million.
- Supply will decrease by 5.8 million barrels per day within the year.
- The forecast for demand recovery in 2027 has been reduced from 2.6 to 2 million barrels per day.
- Refinery throughput in October is expected to drop to a seasonal low of 81.3 million barrels per day, with a projected rise to 84.6 million by year-end.
The main risk for refineries and fuel companies remains middle distillates. According to the agency's estimates, global diesel exports have decreased by approximately 700,000 barrels per day. Tension in the gasoil market is expected to last until 2027.
Diesel Deal Between Russia and the US: New Flows of Oil Products
A major topic in the oil products market is the agreement between the presidents of the US and Russia on October 9 regarding the supply of Russian diesel to American and global markets. The US Treasury has issued a temporary license for transactions involving Russian diesel until April 7, 2027.
- Volumes: 300,000 tons in October, 500,000 tons in November, 1 million tons in December, with the potential to reach up to 3 million tons per month in the future.
- Regulation in Russia: restrictions on diesel exports are being lifted early. The ban on gasoline exports remains until January 31, 2027. The government is also discussing restrictions on LPG exports.
- Supply Mechanism: According to Alexander Novak, the energy ministries of both countries are coordinating a contract and a supply mechanism that takes sanctions against major Russian oil companies into account.
- Market Reaction: US diesel futures have decreased by approximately 5%. In Europe, the effect was short-lived, as the volumes are insignificant compared to the shortage caused by the crisis in the Persian Gulf.
Refineries and the “Energy Truce”: The Pause Has Ended
The “energy truce” announced on October 11 between Russia and Ukraine has essentially collapsed. Kyiv paused strikes on Russian refineries for three days, after which Ukraine accused Moscow of a mass attack on its energy system and announced the resumption of strikes. In September alone, 12 major Russian refineries were hit. Facilities that are either halted or operating at reduced capacity account for nearly a quarter of Russian refining. For oil product exporters, this poses a key risk: the volume of the diesel deal directly depends on the condition of the refineries.
Gas and LNG: Europe Enters Winter with Supply Shortages
The European gas market remains under pressure. TTF futures are trading around €85–87 per MWh, the highest since December 2022 and almost three times higher than a year ago.
- EU underground storage is approximately 73–74% full, with a five-year average of about 89%.
- Brussels has lowered its storage filling target from 90% to 80%.
- Qatari LNG supplies to Europe are nearly nonexistent. The Asian indicator JKM exceeds $25 per MMBtu, and Europe is competing with Asia for every shipment.
- Some analysts still expect a correction. Citi's base forecast for Q4 is €56 per MWh.
Coal, Electricity, and Renewable Energy: Two Poles of Energy Security
High LNG prices are bringing coal back into the energy mix in Asia. The price of Newcastle thermal coal is hovering around $150 per ton. In early October, it reached $152.20, the highest since October 2024, and has risen approximately 45% year-on-year.
Simultaneously, the growth of renewable energy is accelerating:
- In Australia, rooftop solar stations set a generation record of 17.5 GW on October 11, with the share of solar in consumption reaching 72%;
- The volume of Australian renewable energy projects with approved investment decisions has already exceeded 5 GW for 2026, marking an annual record;
- In Europe, energy companies are combining solar generation with storage solutions to reduce dependence on gas during peak hours;
- On October 29, the IEA will present the Renewables 2026 report with updated capacity forecasts.
What Matters to Energy Sector Investors on October 16
- Strait of Hormuz. New incidents could quickly drive Brent back up to $107–110 per barrel.
- Sanctions against the “shadow fleet.” An official US decision could reduce freight rates and exert downward pressure on oil prices.
- First Supplies of Russian Diesel. These will serve as an indicator for crack spreads and refining margins.
- Corporate Agenda. On October 16, Gazprom Neft will issue yuan-denominated bonds at a rate of 8.3%. Shares of Sovcomflot are reacting to signals regarding the easing of sanctions.
- Political Calendar. Until the US midterm elections on November 3, Washington will strive to lower fuel prices.
The takeaway from the week: the global oil, gas, and oil products market remains a seller's market. The geopolitical premium, diesel shortages, and low gas stocks in Europe support prices. Easing sanctions and new logistical schemes only partially alleviate the tension. For energy sector participants, flexible risk management remains a key tool.