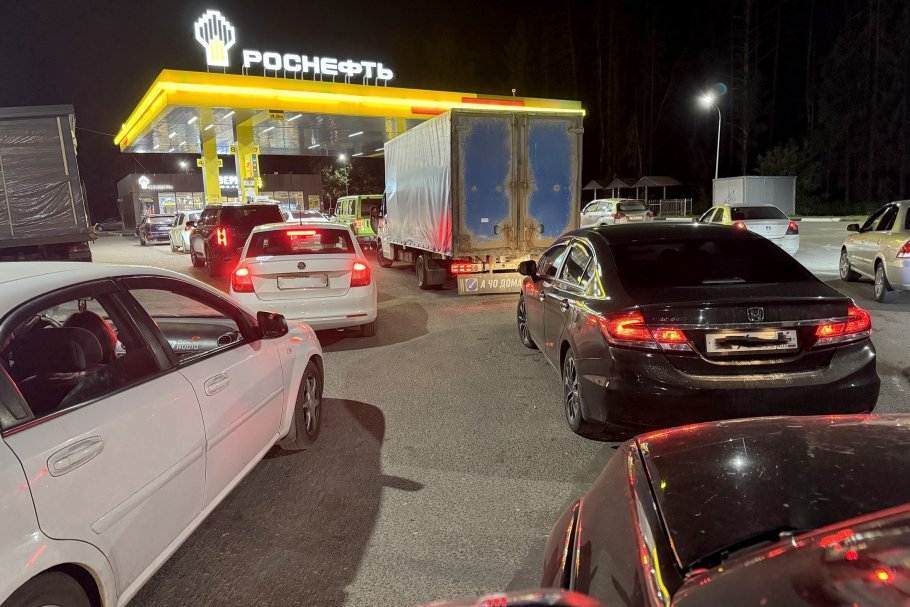
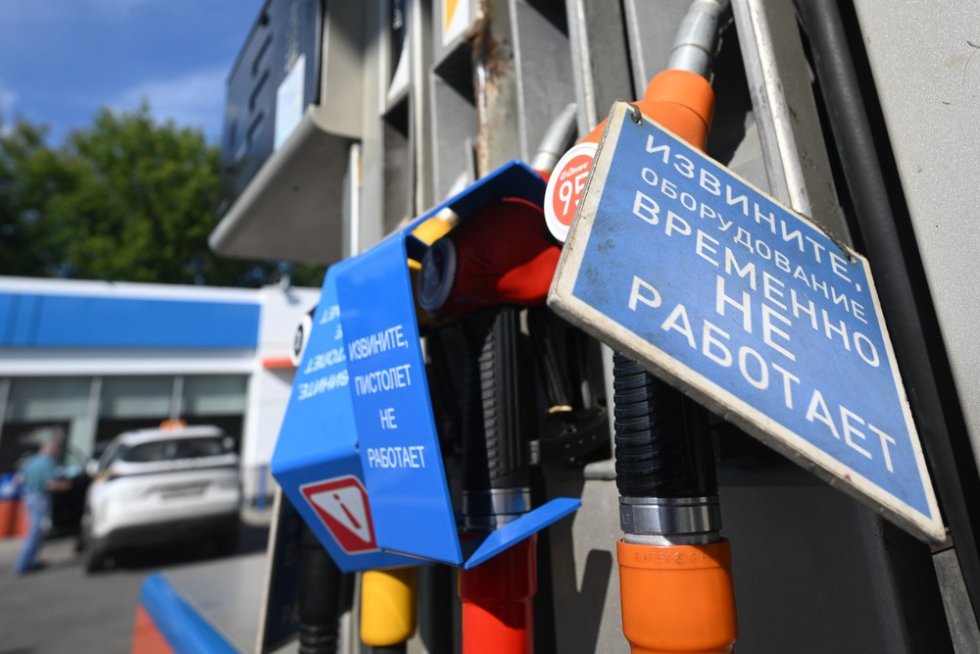
The fuel availability situation at filling stations (FS) is gradually normalizing. While queues still persist in some areas, there is no shortage of petrol, and certainly, there are no issues with diesel, which were generally absent in most regions even at the end of summer. The measures implemented by regulators to stabilize the market have proven effective, and fuel consumption in Russia has begun to decline.
Demand for petrol is decreasing after the holiday season, while diesel fuel (DF) is seeing declining demand as agricultural activities wind down. Logically, prices at the FS should also start to decline slightly. This was the case in mid-September, but by October, prices began to rise again, first for petrol and then for diesel. Notably, fuel prices are increasing at the filling stations of large oil companies, which had previously restrained price growth during August and September, maintaining them at the lowest possible levels.According to the Moscow Fuel Association (MTA), in the capital and the surrounding area, petrol grades AI-92 and AI-95 rose by more than 1 ruble on average over two weeks, while DF increased by 40 kopecks. During the week of October 6 to 12, fuel prices went up only at the filling stations of vertically integrated oil companies (VIOC), which control the entire cycle of working with oil - from exploration and extraction to processing and retail sale of fuel. National statistics for the last week from Rosstat are not yet available; they will be released on Wednesday evening. Additionally, Rosstat does not provide breakdowns by different FS networks, publishing data only on overall price dynamics. However, the agency has already noted the resumption of price increases for petrol since late September. In August and September, the biggest contribution to the retail price rises was made by independent FSs that do not belong to large oil companies. They account for over half of all filling stations in Russia, primarily concentrated in the eastern part of the country, though they account for less than half of fuel sales by volume.
In August and September, independent FSs were most frequently closed due to fuel shortages. These stations do not have the capacity to maintain large reserves of petrol and diesel, nor do they have a substantial financial cushion to weather periods of unfavorable market conditions.
It is not surprising that the highest price increases for petrol and diesel were observed here. To date, the price difference for the same grades of fuel between independent FSs and VIOC filling stations can reach up to 40 rubles, and sometimes even more.
There is no shortage of petrol, nor are there issues with diesel, which were generally absent in most regions even at the end of summer.However, prices at VIOC filling stations are now rising. This indicates an increase in the minimum price threshold for fuel and, consequently, the average price level will also rise.
As noted in a conversation with "RG" by Dmitry Gusev, Deputy Chairman of the Supervisory Board of the "Reliable Partner" Association and a member of the expert council for the "FS of Russia" competition, inflationary price growth has not been canceled, and adjusting prices at the pumps of oil companies is a completely normal process. The price level at "independent" FSs remains significantly higher than at VIOC filling stations.
Additionally, as pointed out by Sergey Tereshkin, General Director of Open Oil Market, peak national demand for petrol occurs during the warm months, gradually decreasing with the onset of autumn. However, there is a nuance: economic activity is concentrated in cities where fuel usage rises again after the holiday season, influencing prices.
The bulk of petrol demand is also concentrated in megacities, which means the risks of rising fuel prices will persist, according to Tereshkin. Moreover, the overall market balance remains fragile due to the consequences of unplanned refinery repairs. Diesel prices are traditionally influenced by the transition from summer to interseasonal and winter grades (which are more expensive), suggesting that we may see an acceleration in diesel price increases in the latter part of autumn and the beginning of winter.
The dynamics of prices may also be influenced by fuel imports. Managing Partner of NEFT Research, Sergey Frolov, believes that the share of imported petrol in Russia's consumption is currently quite significant. The economics of imports are mostly negative, and consequently, companies are compelled to raise prices to mitigate their losses.
Demand for petrol is decreasing after the holiday season, while demand for diesel fuel is declining as agricultural work concludes.Regarding diesel, there is no such dependency. In fact, experts agree that even the resumption of diesel exports from Russia will have no adverse impact on retail prices. Russia produces significantly more diesel than the domestic market requires, which is not coincidental as diesel remains the primary export commodity for our refineries.
Tereshkin clarifies that regulators have approved the shipment of the first 500,000 tons of diesel to foreign markets, which is just over 1% of the annual diesel exports prior to 2022. It is unlikely that these volumes will significantly impact the market, even considering the partial attrition of production capacities.
According to Frolov, historically, diesel production in Russia has outpaced domestic consumption by about two to one. Although this ratio has now decreased, the government has opened exports to prevent a backlog of certain plants and resultant declines in refining capacity. This would have happened regardless of the agreements reached between the presidents of Russia and the USA, the expert believes.
In Gusev's opinion, in light of this year's situation, where the world is facing a fuel crisis, numerous measures were implemented in Russia to stabilize the market and restrain prices for petrol and diesel. Without these measures, price increases at the FS could have been much more substantial. However, as a consequence, one cannot reduce price dynamics solely to the balance of supply and demand after applying non-market regulatory measures. There are limitations on price movements in the market, there are subsidies for refineries from the budget, there is a damper to compensate oil producers for supplying fuel to the domestic market at prices below export levels, and there are attempts to target price growth at filling stations at the level of inflation. These factors also influence the dynamics of both wholesale and retail prices. Under the current macroeconomic conditions, it might even be reasonable to freeze retail fuel prices, according to the expert. There is nothing inherently wrong with this, as many oil-producing nations do likewise, including Saudi Arabia.
Given the ongoing fuel crisis globally and record rising prices for oil, petrol, aviation fuel, and diesel in nearly all countries, it would not be reasonable to expect substantial decreases in prices at FSs in Russia alone. They might decline slightly in November and December, although at year-end, oil companies begin to factor in the planned increases in fuel excise taxes for the following year into their prices. This will also act as a factor restraining price reductions.
Source: RG.RU