Top News of the Day: Key Events in the Energy Sector
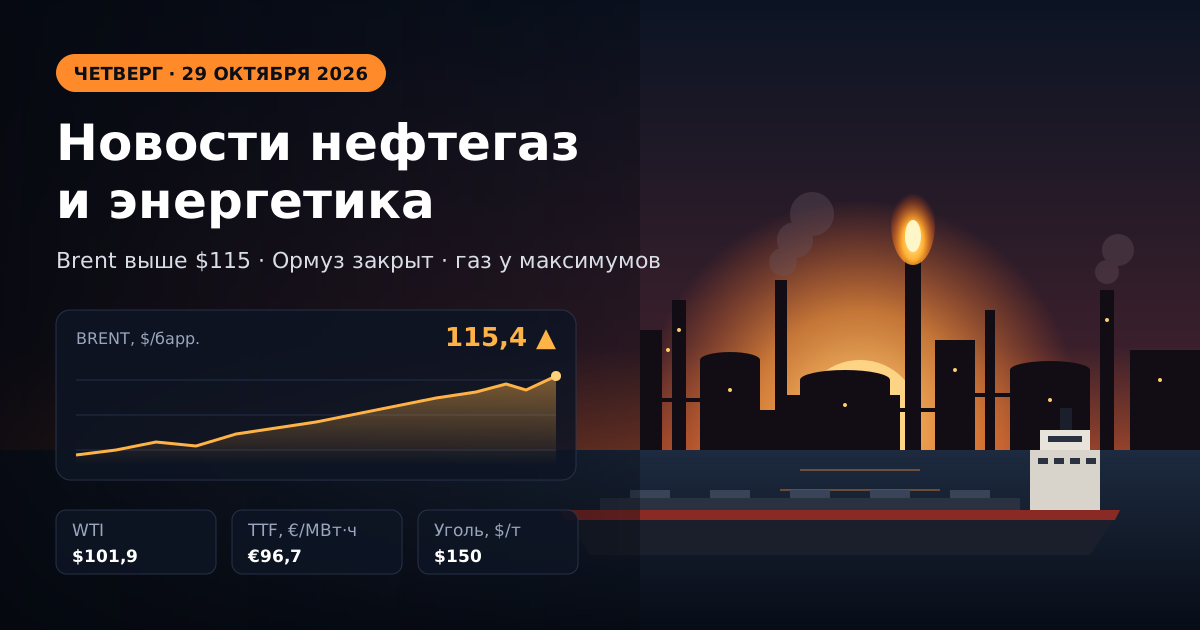
- Brent Oil gained about 3% on Thursday, reaching intraday highs of $112.68 per barrel; WTI briefly surpassed $100.
- The U.S. and Israel, according to U.S. media, have prepared a plan for a "short but intense" operation against Iran following the midterm elections in November.
- The Houthis attacked Saudi facilities, including the Shaybah oil field owned by Saudi Aramco; the U.S. State Department ordered some diplomats to leave Saudi Arabia.
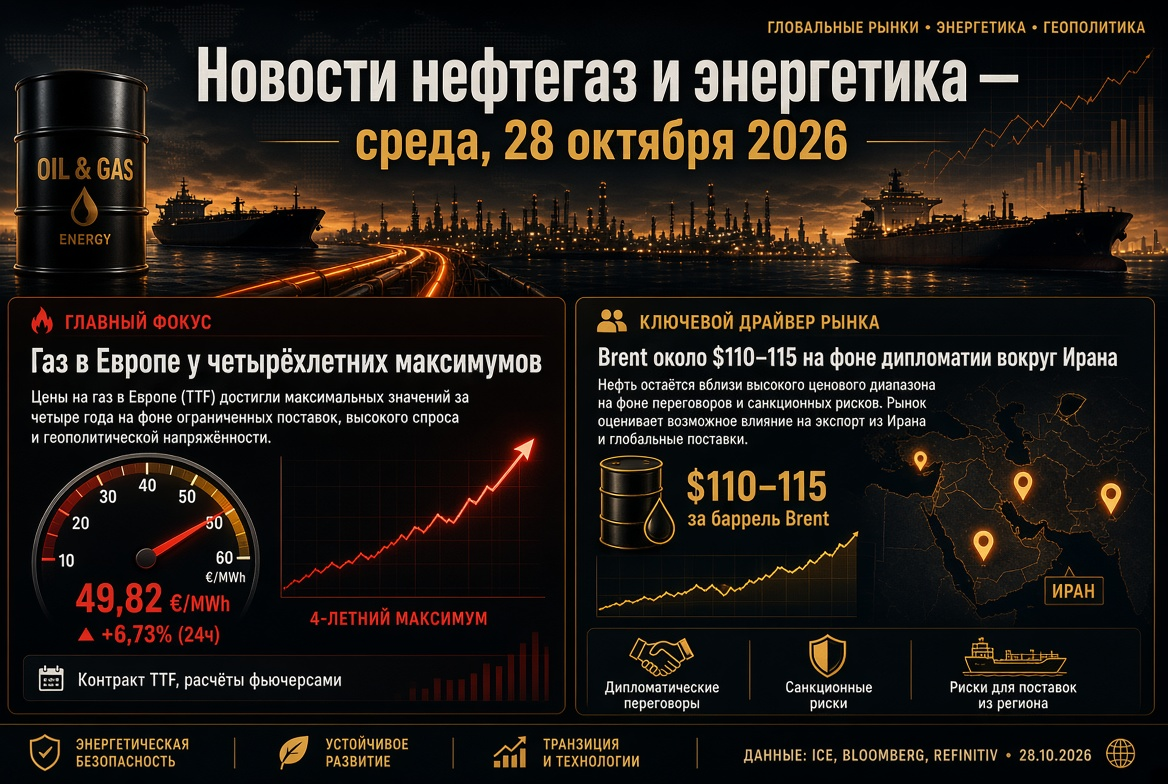
- Gas in Europe: TTF around €87/MWh, with storage facilities filled to about 75% against a seasonal norm of approximately 90%.
- Diesel Crisis: diesel refining margins in Europe and the U.S. remain above $100 per barrel.
Oil Market: Brent at Highest Levels Since May
The key driver of the oil market is the expectation of a new phase of confrontation surrounding Iran. Traders are assessing the likelihood of resumed attacks following the U.S. midterm elections set for early November. Concurrently, the market is reacting to the Yemeni Houthis' attacks on Saudi Arabian infrastructure: in a drone strike on the Shaybah field, two people were killed, and one died at Dammam Airport.
Fundamental data are also supporting prices. U.S. commercial oil inventories decreased by 3.06 million barrels for the week against a forecast decline of 0.8 million, although stocks at the Cushing hub rose by nearly 1 million barrels. Over the past month, Brent has risen more than 8%, and year-on-year, it has increased by approximately 70%.
An important signal for market professionals is the divergence between the paper and physical markets. In the past two weeks, Brent futures have risen by about $10, while prices for physical oil shipments are, conversely, declining. This indicates that a significant portion of the rally is speculative and reflects geopolitical premium rather than a sharp shortage of crude.
Strait of Hormuz: Seven Conditions from Tehran
The situation in the Strait of Hormuz remains a key factor for world oil and LNG. Iranian leadership conditions the full reopening of the route on the fulfillment of seven conditions set by Washington, as outlined in the so-called Islamabad Memorandum. Iran's Foreign Minister Abbas Araghchi stated that should the requirements be met, the strait could be opened on the sixth day, with negotiations with the U.S. resuming on the seventh.
Physical flows have partially recovered:
- The transit of crude oil through the strait is estimated at about 10.3 million barrels per day — approximately 76% of pre-war levels.
- The share of oil products in the cargo flow has fallen to 11% compared to over 20% before the conflict.
- Tehran and the IRGC threaten to extend restrictions to the Bab-el-Mandeb and Suez Canal, creating risks for tanker logistics between Asia and Europe.
OPEC+: Quotas on Paper, Production Below Targets
The OPEC+ alliance has kept its targeted production levels unchanged for November. The quota for Saudi Arabia is 10.5 million barrels per day, for Russia - 9.9 million, and for Iraq - 4.4 million. However, actual production from seven key participants in August was around 25 million barrels per day — about 5 million below the pre-war level of February. Increases in quotas for 2026 have largely remained symbolic.
The next meeting of the alliance is scheduled for 1 November. An audit of production capacities necessary for distributing quotas for 2027 has been postponed due to the ongoing war, hence no significant changes in oil policy are expected until next year. Russian Deputy Prime Minister Alexander Novak expressed confidence that OPEC+ will play a leading role in overcoming the crisis, noting the stability of Russian oil exports.
Oil Products and Refineries: Diesel Shortage
The most constrained segment currently is not crude oil but oil products. The diesel refining margin in Europe has exceeded $100 per barrel, compared to a historical norm of about $20, while in the U.S., records above $117 were recorded in September. The reasons are structural:
- Idle capacity in refining facilities in the Persian Gulf countries;
- Regular attacks by drones on Russian refineries;
- Restrictions on diesel exports for Russian producers until 31 October;
- Export limits on fuel from several other countries, including China.
For investors, this means maintaining high profitability for independent refiners with operational capacities, primarily in the U.S. U.S. energy regulators expect diesel spreads to remain above historical averages until 2027.
Gas and LNG: Europe Enters Winter with Low Stock Levels
The European gas market remains one of the main risks of the season. TTF futures trade around €87/MWh — levels not seen since early 2023. The filling level of European underground storage facilities is about 74–75%, roughly 17 percentage points below the seasonal norm. The EU has already relaxed the mandatory target for filling from 90% to 80%.
The key problem is the shortage of LNG. Attacks on the Qatari Ras Laffan complex have incapacitated two technological lines with a total capacity of 12.8 million tons per year, and QatarEnergy has ruled out constructing pipelines as alternatives to seaborne exports through Hormuz. Europe and Asia are competing for spot cargoes of liquefied gas, and a cold winter could trigger a new price surge.
Russian Fuel Market: Export Restrictions
In Russia, an export ban on gasoline remains in place until the end of 2026, while for diesel fuel, restrictions for producers extend until the end of October. Mid-month signals indicated a partial easing of the oil product export regime, conditional on fully meeting domestic market needs. Refineries are transitioning to produce winter diesel, and authorities are overseeing the formation of reserves for scheduled maintenance periods. A decision on the extension or easing of export restrictions from 1 November will be one of the key events for fuel market participants.
Power Generation, Renewables, and Coal
The energy crisis is accelerating the transition to renewable sources. According to the IEA, in 2026, renewables will surpass coal for the first time and become the largest source of global electricity generation. It is expected that output from renewables will increase by more than 8%, with solar generation adding around 600 TWh and surpassing wind energy. Global electricity demand is set to grow by 3.6% in 2026, with increases of 5.5% in China and 7% in India.
At the same time, expensive gas is supporting coal generation in Asia and partially in Europe: energy systems are leveraging coal as insurance against LNG shortages. The thermal coal market remains at elevated levels, and coal exporters maintain strong positions in the Asia-Pacific region.
Outlook and What to Watch on Friday
As the week wraps up, news in oil & gas and energy will be primarily driven by geopolitics. Energy market participants should pay attention to the following factors:
- Signals from Washington and Tehran regarding Iran and the Strait of Hormuz ahead of the U.S. elections.
- New attacks by Houthis on Saudi oil infrastructure and shipping.
- The dynamics of the spread between futures and physical oil grades as an indicator of rally sustainability.
- Decisions on Russian oil product exports after 31 October.
- Weather forecasts for Europe and the rates of gas withdrawal from underground storage facilities.
The baseline scenario anticipates Brent remaining in the range of $105–115 per barrel until early November. Analysts agree that there is unlikely to be any de-escalation before the U.S. elections; therefore, the geopolitical premium in oil, gas, and diesel prices is expected to persist. A sharp pullback is only possible with real progress in negotiations regarding Hormuz.