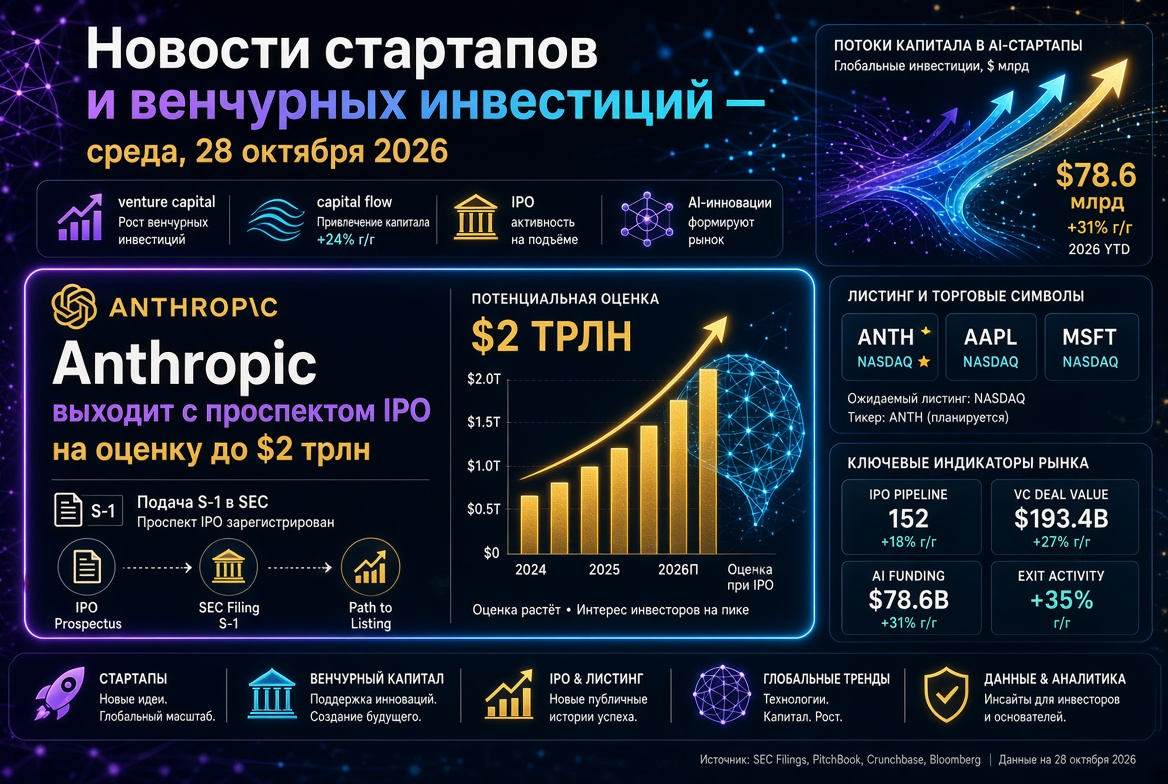
Startup and Venture Capital News — Friday, October 23, 2026: DeepSeek Secures $15 Billion, AI Neo-Labs Soar in Value, and IPO Market Awaits Anthropic
The venture capital market wraps up the week with a series of mega-rounds. Chinese company DeepSeek, according to Bloomberg, has closed a financing round of approximately 100 billion yuan (around $15 billion), marking the largest deal of the year in Chinese artificial intelligence. In the US, investors continue to pour billions into AI neo-labs and applied AI, while public market attention is focused on the potential IPO of Anthropic. For venture funds, this has been a week where capital concentration, high valuations, and expectations for significant exits were particularly evident.
Key Highlights for Friday: Major Events of the Week
- DeepSeek — approximately $15 billion with participation from Tencent, CATL, and industrial capital from China.
- Flapping Airplanes — $1 billion at a valuation of $6 billion; valuation has quadrupled since January.
- Legora — $550 million in a Series E round at an $8.8 billion valuation.
- ASI — $325 million at a $3 billion valuation for AI servicing critical infrastructure.
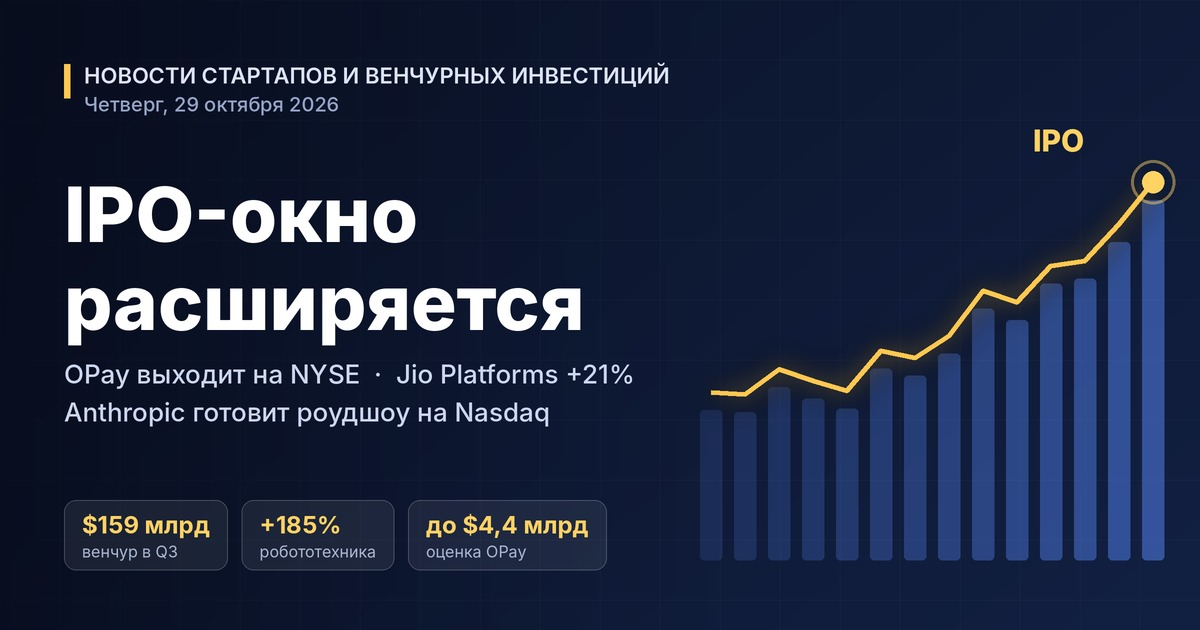
- IPO Market — Jio Platforms completes subscription to India's largest listing ever, Anthropic may publish its prospectus in the coming days.
DeepSeek: The Largest Chinese AI Round of 2026
Initially, DeepSeek aimed to raise about 50 billion yuan, but investor demand allowed the amount to be doubled. According to Chinese business media, the pre-money valuation of the company was around 500 billion yuan (close to $70 billion), while the post-money may reach approximately $84 billion. Key participants in the deal include:
- existing shareholders — Tencent, CATL, IDG Capital;
- new investors — predominantly industry capital, including entities from SMIC and Geely;
- target use of funds — expansion of data centers and development of open models.
Meanwhile, DeepSeek is preparing for an IPO on the Shanghai STAR Market with a listing horizon set for 2027. For global venture investors, this signals that China is establishing its own funding circuit for AI, relying on strategic rather than financial capital.
AI Neo-Labs and Vertical AI: Valuations Growing Faster than Revenue
The deal for Flapping Airplanes illustrates a new trend — betting on so-called neo-labs that focus on research rather than rapid commercialization. The $1 billion round was led by Index Ventures and Lux Capital, with participation from Sequoia Capital, GV, and Kleiner Perkins. The company, founded at the end of 2025, currently has nothing to sell — investors are buying into the team and the thesis of more efficient use of computational resources.
On the opposite end, we see vertical AI with proven revenue. Swedish company Legora, which develops an AI platform for lawyers, raised $550 million under the leadership of Atreides Management. The company has grown from $1 million to $100 million in annual recurring revenue (ARR) in less than 18 months, with all key existing investors participating — from Accel and Benchmark to General Catalyst.
Applied and "Physical" AI: Capital Shifts to the Operational Layer
The deals at the start of the week indicate a shift in venture capital from models to companies integrating AI into real processes:
- ASI (Boston) — $325 million, Series C, valuation of $3 billion; leader — Spark Capital, with participation from Andreessen Horowitz and affiliated entities from Citadel Securities. Profile — predictive AI for aviation, energy, and defense logistics.
- Pigment (Paris) — $250 million, Series E, valuation of $2.3 billion; the round was led by the Scaleup Europe fund managed by EQT, with the company's ARR exceeding $100 million.
- Arda Industries — $160 million, Series A, valuation of $1.5 billion; founder Bob McGrew, former director of research at OpenAI, is automating the design of assembly lines.
- Eka Robotics — $150 million, Series A, valuation of $1.45 billion; co-leaders of the round — a16z and F-Prime.
- Daytona — $60 million, Series B, valuation of $1 billion; infrastructure for "sandboxes" for AI agents.
In total, four new "unicorns" emerged in just one day on the market — a characteristic indicator of peak phases in the venture cycle.
Fintech and Alternative Funding Structures
The fintech segment is also showcasing an appetite for large checks. Ramp secured $1.85 billion at a valuation of $60 billion; the round was co-led by Thrive Capital, Founders Fund, Sands Capital, and Avenir Growth. Notably, the deal with Otter.ai: the company received $320 million from General Catalyst's Customer Value Fund without selling equity. The funds are repayable with interest as revenue grows. Such non-dilutive instruments are becoming a significant alternative to classic rounds for mature SaaS companies.
Climate Technologies and Energy for Data Centers
The AI boom is fueling demand for energy infrastructure. California-based startup Peak Energy, which develops sodium-ion energy storage systems with passive cooling, raised $108 million in a Series B round led by GM Ventures. The funds will be used to enter the data center power market. In France, Elax Énergie secured €30 million for technology that turns electric water heaters into a flexible resource for the energy system.
IPO Market: The Window is Open, but Selectively
The public market remains a key driver for venture fund exits:
- Anthropic. Western media reports that the company is preparing for a possible IPO in November; Renaissance Capital analysts suggest a prospectus may be published this Friday. The last private round was $65 billion at a valuation of $965 billion in May.
- OpenAI has ruled out an IPO in 2026 and, according to Bloomberg, is negotiating to raise at least $30 billion at an estimated valuation of about $1.4 trillion.
- Jio Platforms is completing subscriptions for its IPO totaling over 30,000 crore rupees on October 23; by the morning of the second day, demand had surpassed supply by 3.5 times, with listing expected on October 28.
- Lycia Therapeutics plans to begin trading on Friday after an IPO of $250 million.
However, the number of IPOs in the US since the beginning of the year is a third lower than in 2025, making the success of large placements critically important for liquidity in the entire industry.
Macro Context: A Record Nine Months for Venture Capital
According to Crunchbase data, global venture investments reached $159 billion in the third quarter of 2026 — 25% lower than in the second quarter, but 53% higher than a year ago. Key figures include:
- $102 billion, or 64% of all venture capital, went to AI companies;
- 27 rounds of $1 billion or more — an all-time quarterly record;
- $679 billion over nine months — the highest in recorded history;
- 57% of the quarterly volume was accounted for by American startups.
Russia and CIS: Market Contraction and Focus on Government Funds
The Russian venture market is moving in the opposite direction. According to the Moscow Venture Fund, in the first half of 2026, the volume of venture investments declined by 48% to 4.6 billion rubles, with the number of deals falling by 45% to 54. Support for startups is primarily provided by development institutions: at the Moscow Startup Summit, the MVF signed agreements for 250 million rubles with expected co-investments of around 1 billion rubles. New instruments include a dedicated fund from the FRIID for startups in the information security sector and the "Creative Venture" fund with a volume of 1 billion rubles.
What This Means for Venture Investors
- Concentration is Intensifying. Capital is gathering around a small number of leaders, and competition for stakes in top rounds is becoming more acute.
- Quality of Revenue is Becoming Decisive. Companies with ARR over $100 million, like Legora and Pigment, receive a premium on valuation.
- The Role of Non-Dilutive Financing is Growing for mature startups aiming to retain founder equity.
- The Anthropic IPO will be a Barometer for all upcoming technology placements through the end of the year.
The venture market enters the final quarter of 2026 with record volumes, but also with increased sensitivity to overheating risks. For investors and funds, the critical question in the coming weeks will be whether the public market can validate the valuations established in private rounds.