Key Highlights Ahead of Trading on October 22
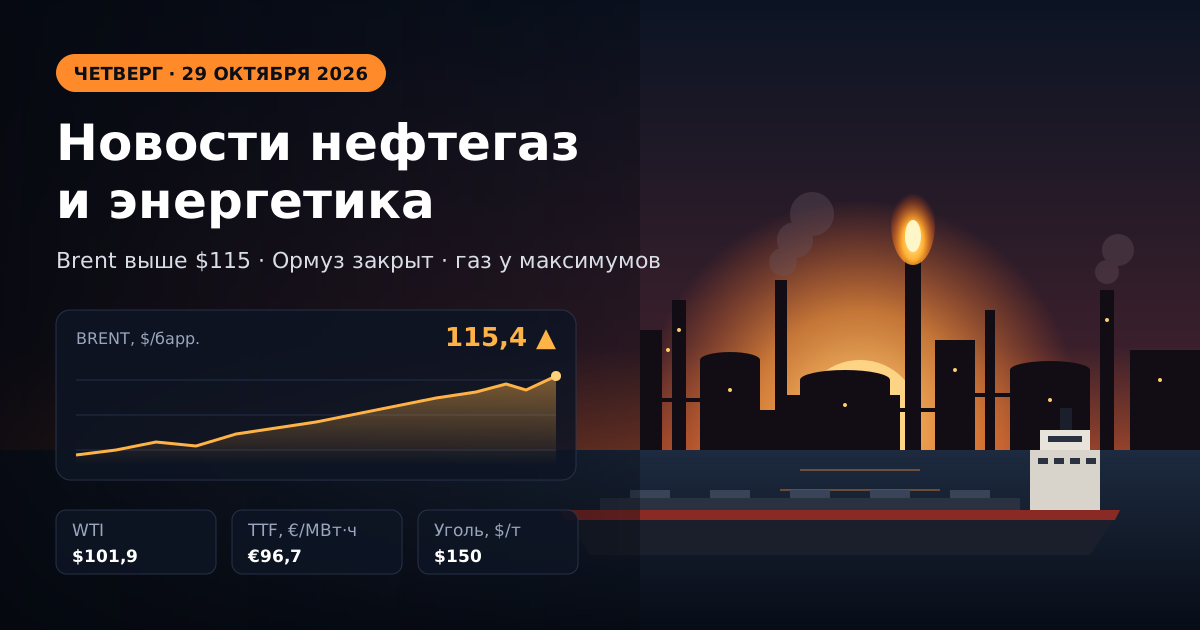
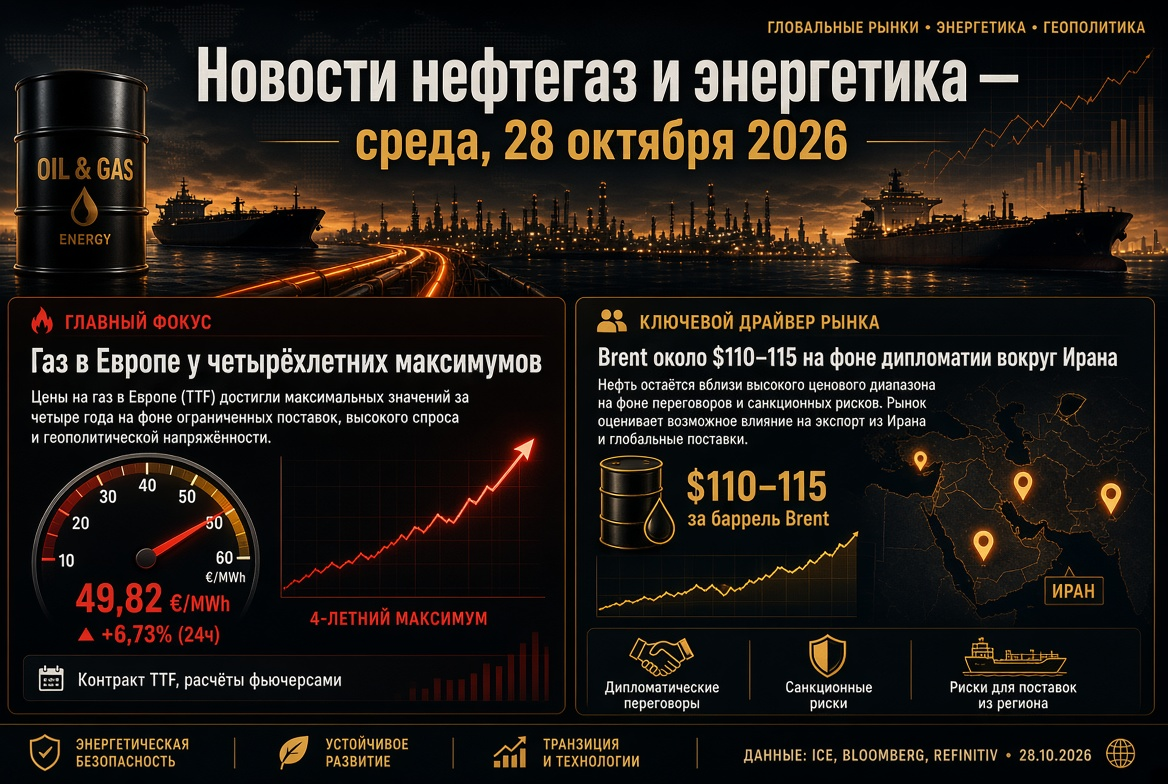
- Oil: Brent – around $110/barrel, WTI – around $99/barrel; oil prices have risen approximately 75% since the start of the year.
- Geopolitics: Tehran has stated that the Strait of Hormuz will remain closed until Washington accepts Iran's conditions.
- Gas: TTF – around €88/MWh, EU storage is approximately 74–75% full.
- Reserves: The US Strategic Petroleum Reserve is at its lowest level since 1982.
- Coal: Newcastle – around $150/ton, reaching highs not seen in two years.
Oil Market: Brent Near Five-Month Highs
Oil prices experienced one of the most volatile days in October. On Tuesday, the December Brent contract fluctuated by more than $6, ranging from $105.95 to $111.99 — a high not seen since mid-May. The drop was triggered by rumors of an impending deal between the US and Iran; however, by Wednesday, oil climbed back above $110 per barrel.
The market is supported by three key factors:
- Declining stocks in the US. Industry data from API recorded a decrease in stocks of crude oil, gasoline, and distillates. The EIA reported a reduction in commercial crude oil stocks by 8.6 million barrels to 415.6 million, about 3% below the five-year average, a week earlier.
- Global market deficit. According to the EIA, global oil stocks declined by an average of 1.9 million barrels per day in Q3, and the decrease is expected to continue into Q4.
- Risk premium. Attacks on vessels in the Gulf of Oman keep freight and insurance rates high.
Strait of Hormuz and Tanker War: Diplomacy Stalls
The crisis in the Strait of Hormuz, which began on February 28, has now extended over 230 days. Iranian Foreign Minister Abbas Araqchi confirmed that indirect communications with the US are ongoing through Pakistan and Qatar; however, the strait will remain closed until Washington accepts Iran's terms. US Secretary of State Marco Rubio described reaching a deal as an extremely difficult task, emphasizing that Iran's nuclear program remains a key issue.
Analysts have noted an expansion in the geography of attacks: strikes on tankers are occurring outside the strait, extending into the Gulf of Oman, which threatens the transshipment of oil between vessels. Meanwhile, oil exports from the Gulf states have partially recovered, while LNG shipments remain almost paralyzed.
Saudi Arabia Under Houthi Threat: Risks for Saudi Aramco
The second area of tension arises from attacks by Yemeni Houthis on Saudi oil infrastructure. On the night of October 14, a missile strike hit the headquarters of Saudi Aramco in Dhahran, damaging three upper floors of the administrative tower with no casualties reported. Previously, the Houthis had announced attacks on Aramco facilities in Riyadh and Yanbu. The group has promised to continue targeting the kingdom's oil facilities, maintaining risks for the world's largest oil exporter and regional refineries.
OPEC+: Quotas on Hold, Focus on 2027 Baselines
The seven key OPEC+ countries — Saudi Arabia, Russia, Iraq, Kuwait, Kazakhstan, Algeria, and Oman — have maintained their target production levels for November without changes. The main quotas are:
- Saudi Arabia – about 10.5 million barrels per day;
- Russia – about 9.9 million barrels per day;
- Iraq – about 4.4 million barrels per day.
The actual production of the group in August was around 25 million barrels per day — approximately 5 million below pre-war levels. Decisions from the alliance have limited impact on the physical market: the main discussion is shifting towards auditing capacities and baseline production levels for 2027. Following the UAE's exit from OPEC in May, this process has gained additional significance. The next meeting is scheduled for November 1.
Strategic Reserves: US SPR at Lowest Level Since 1982
The US Strategic Petroleum Reserve has dropped to 283 million barrels — its lowest since October 1982 and about 40% of designed capacity. The US Department of Energy has proposed releasing an additional 17 million barrels as part of coordinated IEA interventions. It is worth noting that in March, 32 countries agreed on a record release of 400 million barrels, and in early October, G7 nations agreed on an additional 100 million barrels of oil and diesel fuel.
For the market, this indicates that the “safety cushion” is being depleted: the subsequent replenishment of reserves will in itself become a demand factor and support oil prices through 2027.
Gas and LNG: TTF at Four-Year Highs
The European gas market remains the main vulnerability in the energy balance. The price at the TTF hub has risen to €88.41/MWh — a high not seen in nearly four years, with prices increasing by over 200% since the start of the year. Key drivers include:
- EU underground storage levels — around 74–75% compared to a seasonal norm of 86–89%;
- Qatari LNG exports in October may drop to 0.6 million tonnes, with QatarEnergy’s force majeure extended until the end of November;
- Unplanned downtime at the Kårstø gas processing plant in Norway.
ING has raised its average gas price forecast for the winter to €73/MWh. The median projection from banks for Q4 is about €71/MWh, which is below market quotes and indicates a persistent risk premium.
Coal, Electricity, and Renewables
The gas shock has revived demand for coal. The Australian benchmark Newcastle is trading around $150 per ton — 45% higher than a year ago; on October 6, prices reached $152.20, the highest since October 2024.
Conversely, Europe's electricity sector shows resilience thanks to renewable energy:
- The average price in the EU day-ahead market fell by 7% — from €103 to €91/MWh;
- Renewable sources accounted for about 73% of electricity production in the EU;
- Solar generation increased by a record 36.4 TWh from January to August.
Renewable energy has effectively mitigated the transmission of the price shock from gas to electricity, enhancing the investment attractiveness of solar, wind projects, and energy storage systems.
Russia: Oil Products, Refineries, and Export Restrictions
The Russian oil products market remains highly regulated. The ban on gasoline exports is in effect until January 31, 2027, and restrictions on diesel fuel exports for producers have been extended until the end of October against the backdrop of postponed maintenance at refineries during the fall. Data on processing volumes and fuel stock exchange sales has been categorized as restricted access information.
High oil prices and a softening of Washington's sanctions rhetoric have driven Russian stocks to their highest levels since mid-June and are bolstering the ruble. Discounts on Russian oil for China have narrowed. Upcoming focus is on the Bank of Russia meeting on October 23.
What Investors Should Watch: Calendar and Scenarios
- October 22: market reaction to fresh EIA data on oil and oil product stocks, weekly statistics on gas stocks in the US.
- October 23: Bank of Russia decision on the key rate.
- November 1: OPEC+ meeting on production policy for December.
- Early November: midterm elections in the US, after which a shift in Washington's policy towards Iran may occur.
The base scenario for the oil and gas sector anticipates Brent to remain in the range of $105–115 per barrel until tangible progress is made in the Hormuz negotiations. A deal between the US and Iran is capable of rapidly diminishing the risk premium, while new strikes on Persian Gulf infrastructure could push oil back to annual highs above $120. For the gas market, key factors will include the weather in Europe and the timelines for resuming LNG shipments from Qatar.